


You've got a growth target, a spreadsheet full of channel spend, and a board asking whether the next move is more marketing or an acquisition. Meanwhile, your finance lead is trying to reconcile ad invoices, deferred revenue, hiring costs, and a target company's books with the same tired workbook. Everyone says “growth and acquisition” as if it's one strategy. It isn't.
Growth is earned customer by customer. Acquisition is bought in a transaction. The two can support each other, but they create different cash demands, risks, accounting work, and hiring requirements. Confuse them and you won't just miss a forecast. You'll hire the wrong people, misread momentum, and explain a very expensive surprise to your board.
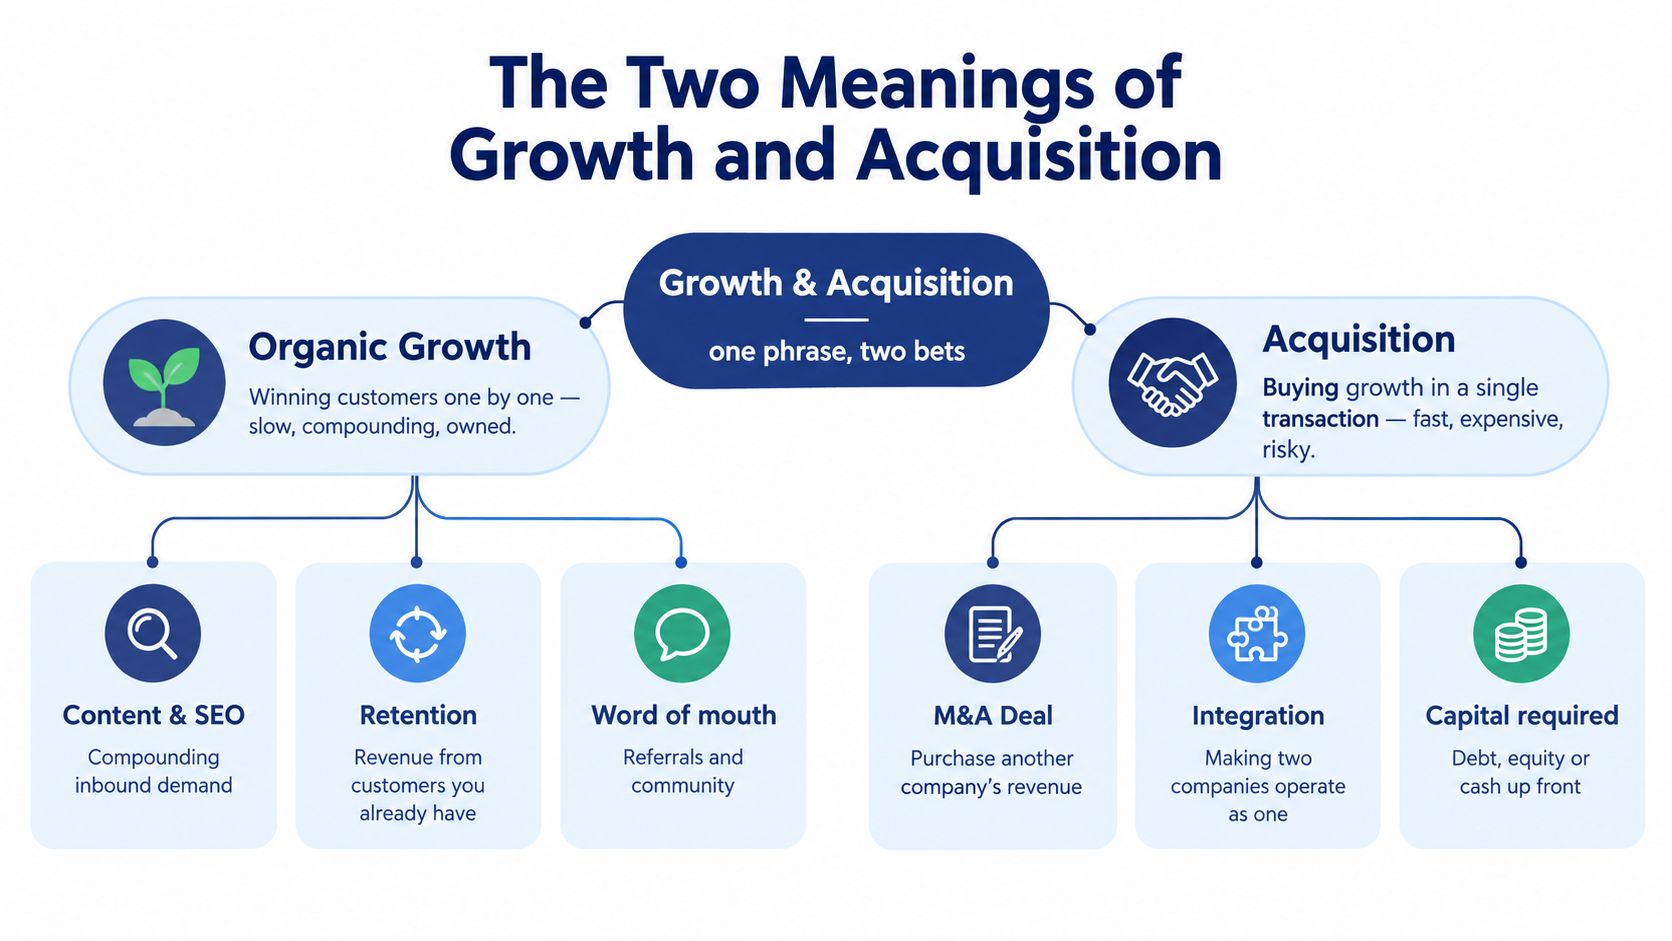
The phrase growth and acquisition contains a nasty little bait-and-switch. It sounds like one polished boardroom objective, but it hides two distinct bets.
Organic growth means winning customers one funnel step at a time. You invest in product, content, SEO, partnerships, sales, onboarding, and retention, then wait for those efforts to produce recurring revenue. The spend usually lands in sales and marketing expenses as it happens. You can turn a campaign down, pause a channel, or redirect a team without asking a lender to bless the decision.
Acquisition, by contrast, means buying another company to obtain revenue, talent, geography, technology, customers, or distribution. The transaction brings a purchase price, legal work, diligence costs, financing, goodwill, possible earn-outs, and integration expenses. The cash can leave before the promised synergies show up.
History makes the distinction hard to ignore. In the United States, merger activity has arrived in repeated waves. During the major 1990s surge, almost 46,000 announced transactions involving at least one U.S. party carried aggregate announced values of $4.7 trillion, according to this historical analysis of the 1990s merger wave. That was acquisition-led expansion at industrial scale, not a clever content calendar.
The first major U.S. merger wave offers an even sharper lesson. Between 1897 and 1904, 4,277 firms were consolidated into 257, while 1,028 firms disappeared into mergers in 1899 alone, as documented in this history of landmark merger waves. Buying growth can reshape a market quickly. It can also reshape your liabilities just as quickly.
Practical rule: Put “build” and “buy” on separate lines in the operating plan. If the team can't explain the cash flow and finance workload for each, the strategy isn't ready.
Organic growth hits the P&L through ongoing operating activity. Acquisition creates a transaction and then an integration program. Your runway model, accounting treatment, hiring plan, and board narrative should reflect that difference from the first draft.
Most startups should default to organic growth. It preserves optionality, forces the product to earn demand, and lets you stop spending when the evidence turns ugly. You can pause paid search on Friday. You can't casually unbuy a company on Monday.
Acquisition wins when you need something you can't build quickly enough, such as a distribution network, a strategic capability, a geographic foothold, or a team with scarce expertise. The premium buys speed, but speed only matters if the integration can keep up.
| Dimension | Organic Growth | Acquisition |
|---|---|---|
| Cost | Ongoing spend across product, marketing, sales, and retention | Large upfront transaction cost plus diligence, financing, retention, and integration expenses |
| Speed | Gradual, with progress built through repeated customer wins | Fast access to revenue, people, customers, or distribution after closing |
| Risk | Channel, product-market fit, churn, and execution risk | Valuation, hidden liabilities, culture, systems, talent retention, and synergy risk |
| Integration friction | Usually limited to internal processes and new hires | Requires financial consolidation, reporting alignment, systems work, legal coordination, and organizational change |
Organic growth often looks expensive because the invoices arrive every month. Acquisition can look efficient because the revenue appears on day one. That comparison is usually nonsense. The purchase price is only the visible part of an acquisition, while organic investment exposes its cost continuously.
Legal fees, quality of earnings work, retention packages, working capital negotiations, escrow arrangements, purchase accounting, and post-close systems work all consume money and management attention. The seller's revenue doesn't arrive with a magic integration button.
A deal can give you customers faster than a new channel can. It can also give you duplicate software, incompatible processes, distracted managers, and a retention problem wearing a nice valuation multiple.
Use acquisition when the target's capability changes your strategic position. Don't use it to avoid fixing a weak product or a leaky funnel. Buying a bad business model gives you a larger bad business model.
Organic growth is usually more reversible. You can shrink a campaign, change a sales motion, or redeploy staff. Acquisition commits capital and attention before you know whether the combined company will work.
That's why the sensible answer is often sequence, not choose. Build a repeatable customer engine first, then acquire a capability or channel that makes that engine stronger. Run both if you must, but keep the accounting and operating plans separate.
Customer acquisition starts before the lead form and ends after the first renewal. Teams that stop measuring at a demo request aren't measuring acquisition. They're measuring activity.
A practical funnel has four stages:
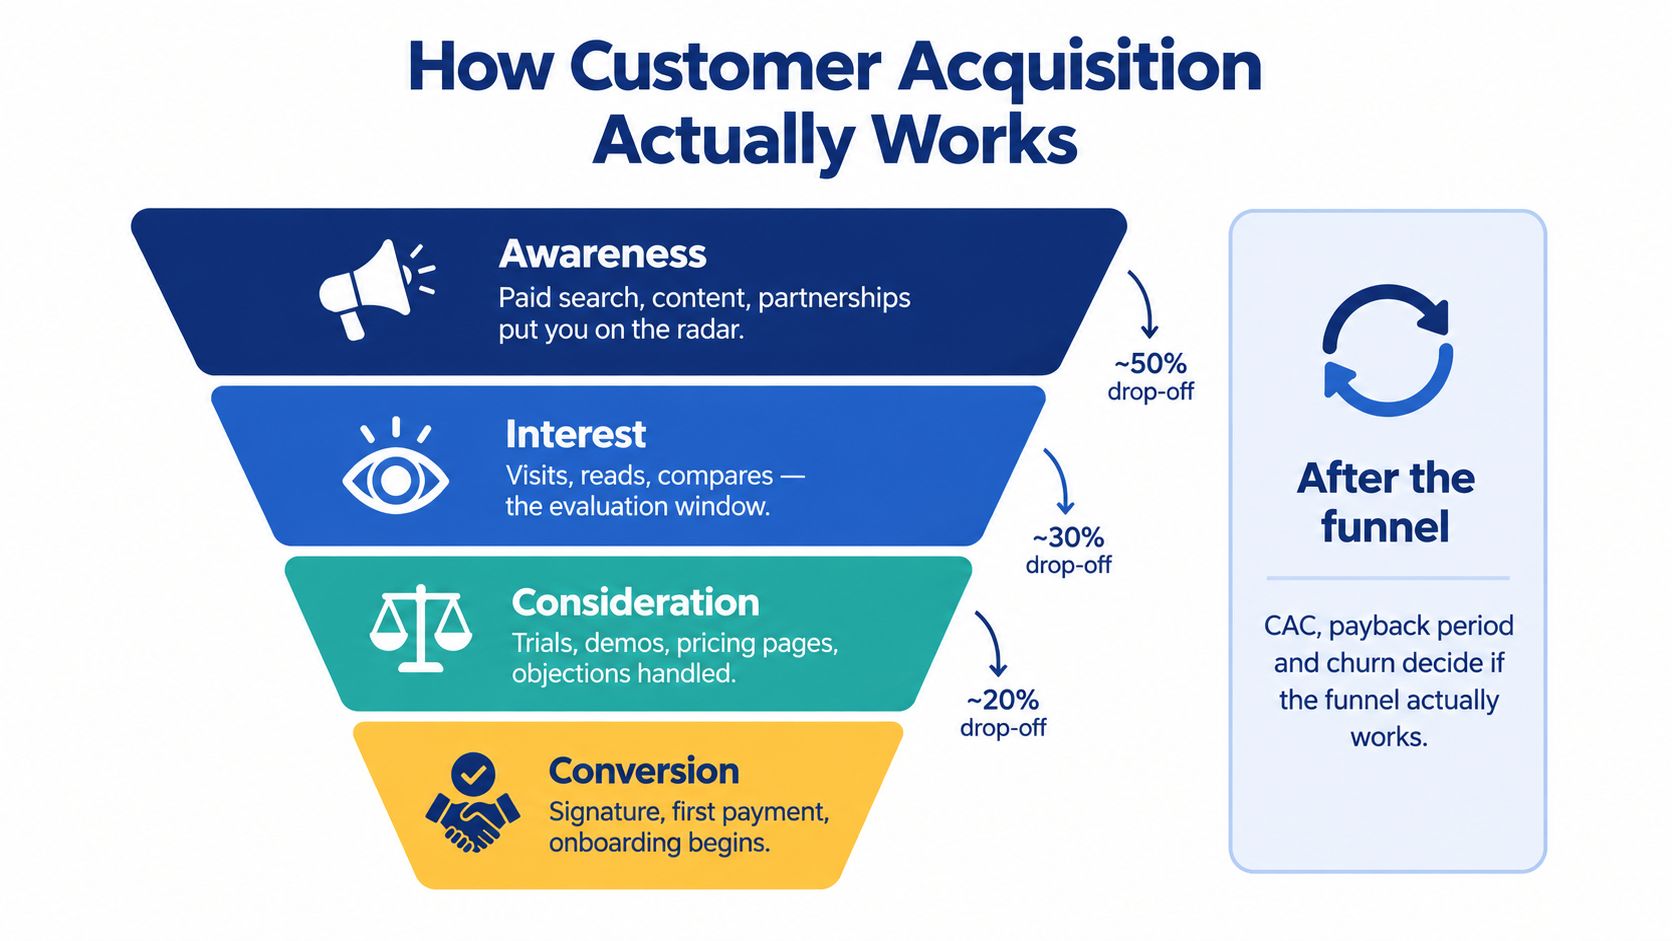
Start with CAC, calculated as total marketing campaign costs divided by total customers acquired. That formula is useful, but only if “marketing costs” includes the costs your finance team can defend. A widely used sustainability benchmark is a 3:1 LTV:CAC ratio, meaning one dollar spent acquiring a customer should produce roughly three dollars of lifetime value, as explained in this CAC and LTV:CAC benchmark guide.
Track at least four views:
The numbers need channel detail. One 2026 B2B benchmark set reports organic CAC around $942 versus paid CAC around $1,907, alongside a 2.2% visitor-to-lead conversion rate, 14% lead-to-SQL conversion, and 27% SQL-to-win conversion, as shown in this B2B customer acquisition KPI benchmark. Your own funnel may look different, but the lesson is straightforward: top-of-funnel efficiency can change blended CAC even when close rates stay the same.
The common traps are familiar. Teams count activated users instead of paying customers, ignore churn when estimating LTV, and credit the final click while organic content or a partner created the demand weeks earlier.
Finance has to allocate spend to the right periods and channels. Marketing can explain the journey, but finance should test whether the journey produces profitable revenue. Otherwise, the company celebrates a low cost per lead while paying more to acquire customers who never stick.
The purchase price is the cheapest part of an acquisition. The integration budget is where deals bleed.
A founder scenario makes the point. You sign a letter of intent with a company that appears to have attractive recurring revenue and a useful customer base. The headline price feels manageable, and the board likes the speed. Then diligence begins.
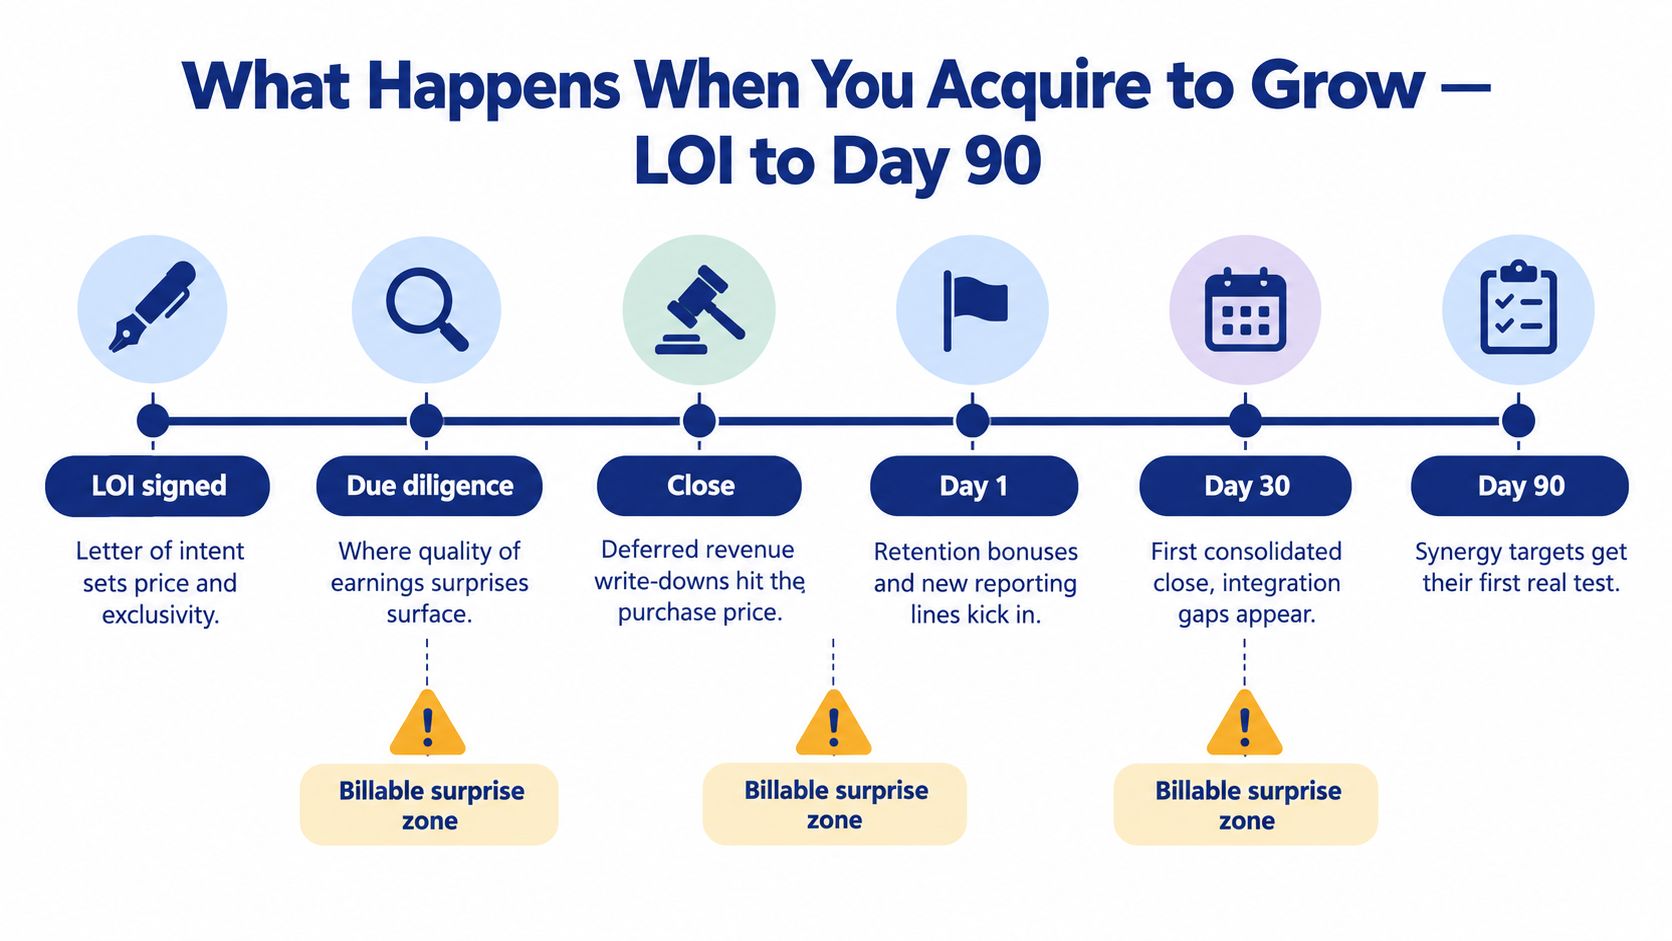
Quality of earnings work may uncover customer concentration, unusual adjustments, weak renewal evidence, or revenue that doesn't behave as the pitch deck implied. A working capital peg can change the amount delivered at closing. Escrow can reduce what the seller receives while protecting you against specified liabilities.
Deferred revenue can also complicate the economics. Under purchase accounting, you may need to write down deferred revenue, reducing the value assigned to the acquired obligation and changing the revenue profile you expected. That's not a footnote. It affects the model your board approved.
A disciplined financial due diligence checklist should cover financial records, tax compliance, receivables, debt, liabilities, and equity structure before anyone starts congratulating themselves.
At close, retention bonuses may become accrued obligations. Reporting lines change. Payroll, benefits, bank access, approval workflows, customer communications, and revenue reporting need owners. If the businesses use different systems, the first consolidated close becomes an audit of every assumption you made during diligence.
By Day 30, integration gaps tend to become visible. Duplicate tools remain active, customer data doesn't reconcile, and managers discover that “synergy” means somebody has to do two jobs while the new structure settles.
By Day 90, you should test the synergy case against actual costs and delivery, not optimism. Goodwill may later face impairment testing if the acquired business underperforms or its expected benefits deteriorate.
For a useful example of strategic redirection before a major outcome, read this pivot strategy BAMF analysis. The broader lesson is that strategic position matters more than the vanity of just owning another company.
A finance team shouldn't merely report the score after the game. It should define the scoreboard before marketing spends the money or the deal team signs the papers.
For organic growth, the operating stack starts with CAC, LTV, payback period, conversion by channel, retention, and the magic number. Weekly owners should know which channels generate qualified pipeline, where prospects drop, how quickly new customers recover acquisition cost, and whether retained revenue supports the original LTV assumption.
Board-facing metrics answer a different question: is the growth engine becoming more efficient and durable? Finance should present trends in unit economics, gross margin, net dollar retention, cash conversion, and the relationship between growth investment and recurring revenue.
Acquisition reporting adds revenue recognition treatment, goodwill impairment triggers, return on invested capital, and accretion or dilution. Finance must separate acquired performance from the buyer's pre-existing performance, track integration costs, and show whether the transaction improved the economics promised in the investment case.
That distinction matters because a consolidated revenue line can hide a deteriorating acquired business. If the target's revenue grows while margins fall and retention weakens, the deal may be moving the company forward on paper while damaging it underneath.
For a practical overview of KPI definitions and accounting ownership, use this accounting KPI guide. For readers who want a broader framework for choosing and interpreting company measures, misurare il successo con Spark offers a useful companion perspective.
The number founders most often misremember is net dollar retention. It starts with an existing customer cohort, then accounts for expansion, contraction, and churn. New logo revenue doesn't rescue a weak cohort. Finance should own the definition, cohort boundaries, timing, and reconciliation to the ledger.
Board rule: If two departments calculate the same KPI differently, neither department owns it.
Marketing can own channel execution. Sales can own pipeline progression. Product can own activation. Finance should own the definitions that connect those activities to recognized revenue and cash.
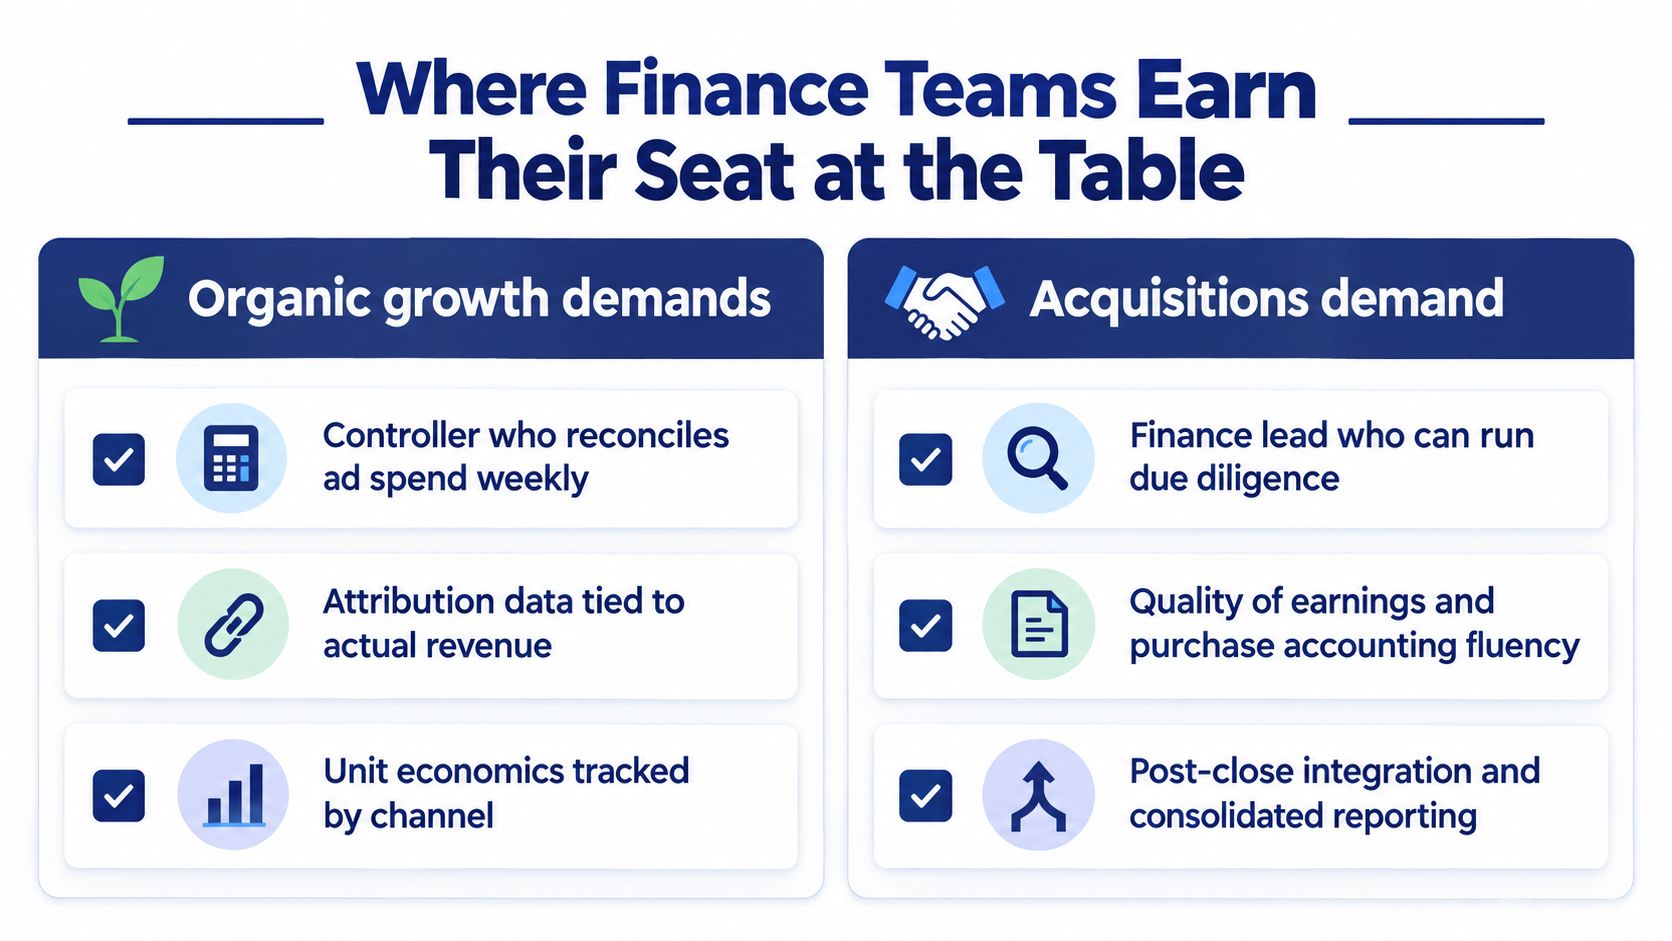
Organic growth creates a particular kind of finance workload. Somebody needs to reconcile advertising spend weekly, connect attribution data to actual revenue, review channel-level unit economics, and separate a promising experiment from an expensive hobby.
Acquisition creates a different workload. You need someone who can run diligence, challenge quality of earnings, model synergies, understand purchase accounting, coordinate the close, and produce consolidated reporting after Day 1. A bookkeeper who keeps the ledger tidy may be excellent, but that doesn't automatically make them the right person to lead a transaction.
For a smaller company, the right answer may be a remote accountant or fractional CFO rather than a full internal department. The workload is often spiky. You may need deep diligence support for a transaction, then a steadier close and reporting rhythm afterward.
Organic growth demands:
Acquisitions demand:
The hiring triggers are practical. Crossing $3M ARR, pursuing a first acquisition over $500K, preparing for a first audit, or committing to your first material channel spend should force a finance-capacity review. Those thresholds don't guarantee a hire, but they're strong signs that founder-led spreadsheets have reached their useful limit.
A fractional finance leader can also help when the company needs planning and operational decision support without a permanent executive structure. Fractional CFO services are one route, alongside an internal controller, a specialist accounting firm, or a blended team.
Don't make the decision in an investor update. Make it against runway, timing, team capacity, and unit economics.
Use this blunt checklist.
For a more detailed way to assess the strategic upside of a target, review this guide to evaluating growth potential for acquisitions. Then challenge its conclusions with your own retention data, integration plan, and downside case.
A target with attractive revenue may still weaken your company if it carries poor margins, high churn, or customers who don't fit your product. Bought growth that erodes margin is expensive churn in disguise.
The same goes for organic growth. Traffic, signups, and pipeline can look impressive while paying customers fail to activate or renew. Growth earns the label only when the economics survive contact with the ledger.
Ask this before writing a check, hiring a channel team, or increasing ad spend:
Does this move compound, or does it just move?
Organic growth compounds when each customer makes the next customer easier to win, through referrals, stronger proof, better product data, or durable demand. Acquisition compounds when the target's capability, distribution, or market position accelerates everything downstream.
If you can't explain the compounding mechanism, the spend is a guess. A larger customer count doesn't prove a better business. A deal close doesn't prove strategic progress. Both need a measurable path from investment to durable revenue, margin, retention, and cash.
Growth is earned. Acquisition is transacted. Finance has to instrument both before the bet, during the execution, and after the result arrives. That means separate models, clear owners, consistent definitions, and reporting that doesn't blend the good news with the expensive news.
Most founders over-buy and under-build because buying feels like progress while building feels like waiting. Sometimes waiting is exactly the disciplined choice. If the math doesn't justify the invoice, patience isn't cowardice. It's capital allocation.
HireAccountants helps companies find pre-vetted accountants and finance professionals for bookkeeping, accounting, analysis, and finance leadership support. If your next growth push or acquisition is creating work your current team can't absorb, visit HireAccountants to explore flexible finance talent aligned with your needs.
Let's simplify your finances today!