


The board meeting starts in twenty minutes. Your books are still open, payroll hasn't reconciled cleanly for months, and the cash forecast is “directionally correct,” which is finance-speak for “please don't ask follow-up questions.” Meanwhile, a diligence team is circling your accruals and someone has discovered an intercompany balance nobody can explain.
That's not a bookkeeping inconvenience. It's a controllership failure. Accounting controller duties begin where tidy checklists end, with ownership of the numbers when they're late, wrong, unsupported, or impossible to defend.
The moment usually arrives during an unpleasant meeting. A board member asks why cash moved differently from the forecast. The CFO opens a spreadsheet with three versions of the same number. Your staff accountant says the payroll reconciliation is “almost done,” while an investor's diligence request asks for support behind an accrual nobody remembers approving.
Then the surprises stack up: an intercompany imbalance appears during consolidation, an audit adjustment eats time your team doesn't have, and board members start treating every figure as a draft. A finance team of one or two staff accountants can keep transactions moving, but it can't indefinitely absorb close ownership, controls, reporting, audit preparation, and planning.
A controller becomes necessary when the company needs one person accountable for financial truth, not another pair of hands entering invoices. A major 2025-2026 role study found that 69% of controllers said they had primary responsibility for bookkeeping and reporting, reinforcing that the role still anchors core recordkeeping and reporting while expanding into governance and leadership (controller role study).
Founder test: If nobody can explain what broke, who owns the fix, and what evidence proves it's fixed, you need controllership, not another spreadsheet.
The work falls into six practical buckets: monthly close, financial reporting, internal controls, budgeting and FP&A, team and vendor leadership, and the build-versus-buy decision. This guide treats the role as ownership of outcomes when things go wrong, because that's when the title earns its keep.
A controller owns the accounting function, the integrity of the financial records, and the timeliness of reporting. The controller normally reports to the CFO and manages staff accountants, bookkeepers, and the processes that turn raw transactions into reliable statements.
That scope differs from both neighboring roles. The CFO owns capital structure, investor communication, strategic finance, and the financial narrative presented to the board. The staff accountant executes transactional work, reconciliations, and journal entries under controller supervision. The controller is the operating owner between those two layers.
| Responsibility Area | Controller | CFO | Staff Accountant |
|---|---|---|---|
| Close process | Owns calendar, review, reconciliations, and sign-offs | Reviews results and resolves executive issues | Completes assigned close tasks |
| Financial statements | Prepares and validates GAAP reporting | Uses outputs for decisions and board communication | Supplies schedules and entries |
| Internal controls | Designs, documents, and tests controls | Sets risk appetite and governance expectations | Follows approved procedures |
| Capital strategy | Supplies accurate financial foundations | Owns fundraising, financing, and investor narrative | No ownership |
| Audit relationship | Leads requests, evidence, and remediation | Manages executive and board implications | Produces supporting workpapers |
| Daily transactions | Oversees the system and exceptions | Usually stays out of transaction processing | Records, reconciles, and investigates |
Controllers oversee the close, prepare GAAP financial statements, maintain controls, manage auditors, own revenue recognition and complex accruals, supervise AR and AP oversight, coordinate tax work, and build FP&A capability once the books are clean. They don't set company strategy, raise capital, own product or sales metrics, or act as the bookkeeper.
Career references describe the position as a broad control-and-reporting function covering closes, GAAP compliance, internal controls, audits, and accounting-team leadership (controller responsibilities and reporting scope). My decision rule is blunt: hire a controller when the pain is reporting quality and control discipline; hire a CFO first when the pain is fundraising narrative and capital strategy.
A close isn't “the books are done.” It's a controlled sequence with owners, deadlines, review evidence, and an explanation for material movements. The controller signs their name to the process, even when someone else performs the task.
A workable calendar looks like this:
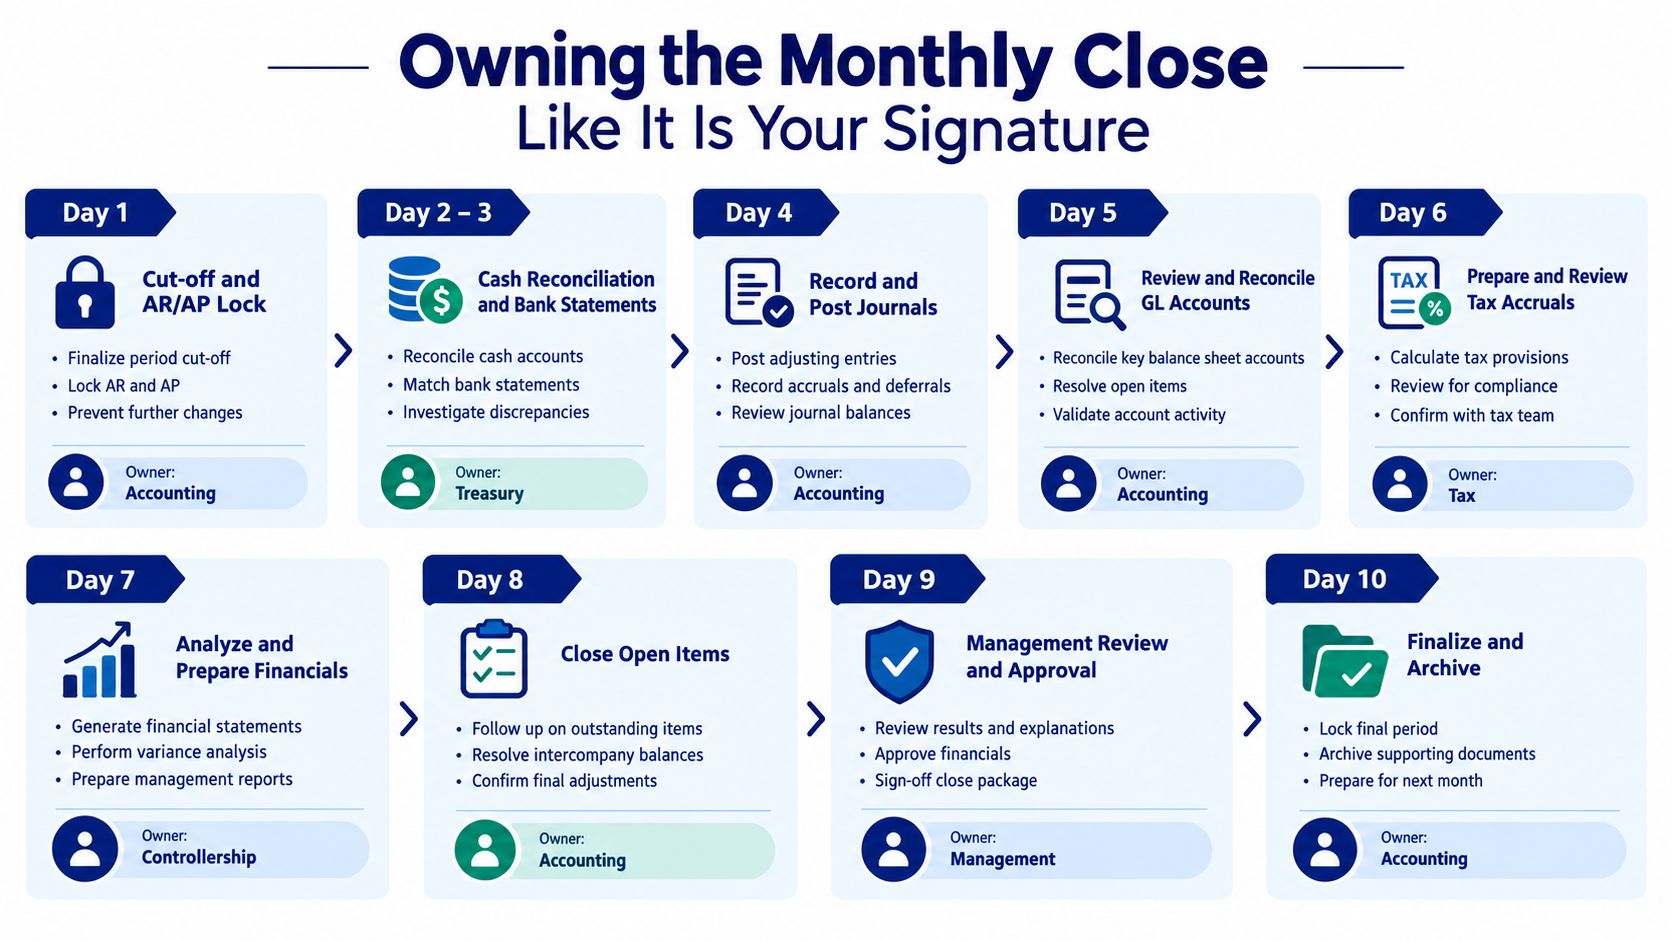
For startups and SMBs, I recommend closing within 7 to 10 business days, then tightening the cadence as transaction volume and entity complexity grow. The common failures are predictable: missing reconciliations, revenue cutoff errors that trigger restatements, intercompany balances that surface only during consolidation, and subledgers that stopped agreeing with the general ledger weeks ago.
A strong close function gives every task a named owner, due date, reviewer sign-off, and supporting documentation. The controller approves material accruals and estimates, validates balance-sheet integrity, and explains significant period-over-period variances before leadership sees the package (close ownership and evidence discipline).
Financial reporting is where controller competence becomes visible to people who aren't accountants. The monthly package should include the P&L, balance sheet, cash flow statement, equity rollforward, and flux commentary, with every significant figure tied to source evidence.
The controller also consolidates multi-entity results, resolves intercompany entries, and prepares GAAP-compliant statements. Depending on the business, that means handling ASC 606 revenue recognition, ASC 842 leases, and ASC 805 business combinations. Public-company exposure adds SEC-adjacent work such as 10-Q support, cap-table reconciliation, and 409A inputs when relevant.
| Reporting Duty | Sample Job Description Bullet |
|---|---|
| Monthly statements | Prepare monthly GAAP financial statements with flux analysis versus budget and prior year, reviewed by CFO within five business days of period end. |
| Consolidation | Own multi-entity consolidation, intercompany eliminations, and supporting reconciliation schedules. |
| Revenue recognition | Maintain ASC 606 policies, contract schedules, deferred revenue, and documented judgments. |
| Lease accounting | Maintain ASC 842 lease schedules and reconcile balances to the general ledger. |
| Audit support | Maintain an audit-ready tie-out binder with source documentation for material accounts. |
| Regulated reporting | Support SEC reporting, cap-table reconciliation, and 409A inputs when applicable. |
The controller's work stops at reliable accounting outputs and interpretation of what changed. FP&A can use those outputs to model scenarios, evaluate hiring plans, or assess operating performance, but it shouldn't rewrite the historical record to make a forecast look prettier.
A useful job-posting line is: “Own the monthly reporting package, including GAAP financial statements, consolidation, account tie-outs, and clear variance commentary for executive review.” Another is: “Maintain accounting policies and supporting schedules for complex transactions, with documentation sufficient for audit and financing diligence.”
The silent failure is the one you meet during an audit: a GAAP misstatement nobody caught because the report was never reconciled to source evidence. Use compliance with GAAP guidance as a reference point, but make the controller own the actual schedules, judgments, and review trail.
You don't need a corporate bureaucracy to need controls. You need controls because humans make mistakes, access rights linger, and the person who enters a payment shouldn't approve it too.
Start with the controls that catch expensive errors:
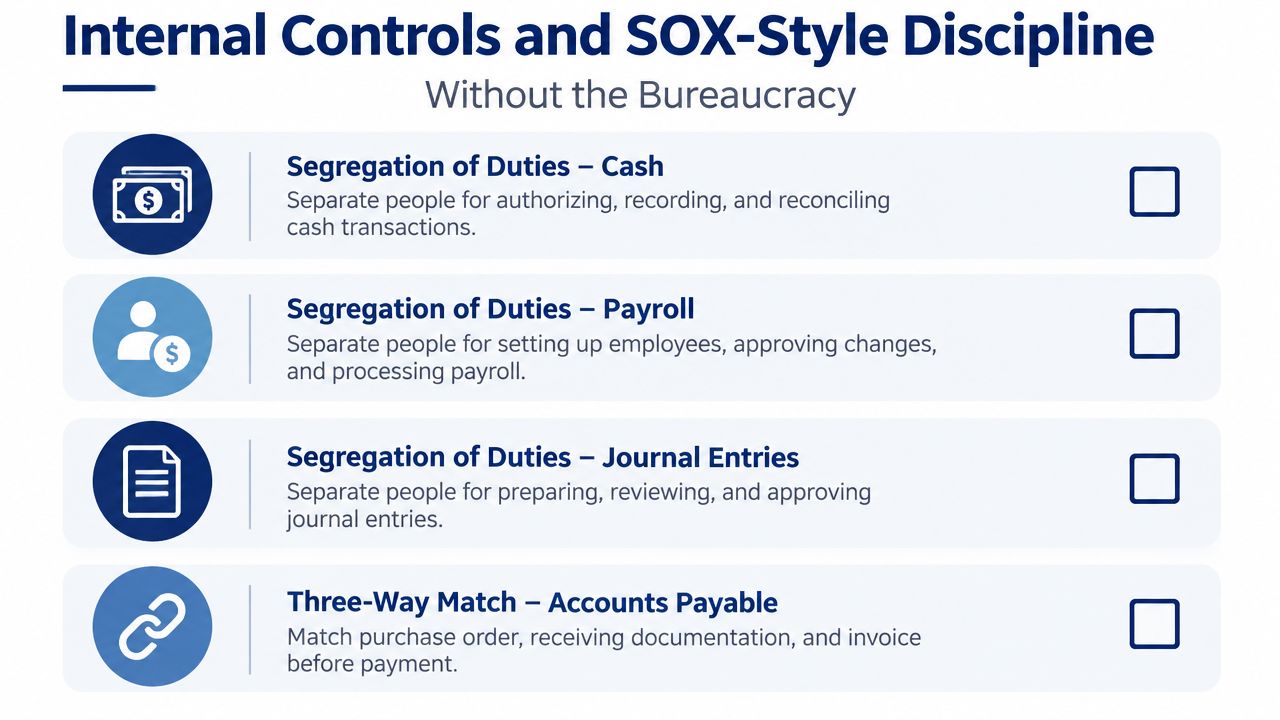
I've seen an AP clerk cut the same vendor three checks because duplicate detection was absent. The fix wasn't a motivational speech. It was duplicate-invoice review, vendor-master controls, and an independent payment approval.
Another founder approved their own corporate-card charges without realizing the workflow allowed it. A simple approval matrix and delegated reviewer would have caught the conflict. An equity grant booked off-ledger in a spreadsheet needed a controlled equity schedule, reconciliation to the ledger, and review by someone who understood the cap table.
Practical rule: Controls should be boring to follow and painful to bypass.
That discipline helps a company withstand audit requests, financing diligence, and a SOC 1 review without recreating a year of history. The controller's job isn't to make every employee fill out a form. It's to identify where money, access, estimates, and reporting can fail, then install evidence that catches the failure early.
A controller earns a broader seat only after the books deserve trust. Before that, forecasts are often elaborate guesses built on numbers that haven't reconciled. That's how a company misprices runway while congratulating itself on a polished dashboard.
The operating rhythm should include an annual budget build, monthly actuals-versus-budget review, and quarterly reforecasting. A 13-week rolling cash forecast gives management a practical view of collections, vendor timing, payroll, and financing needs. Scenario models then pressure-test runway, hiring, compensation, and spending assumptions against the cap table and operating plan.
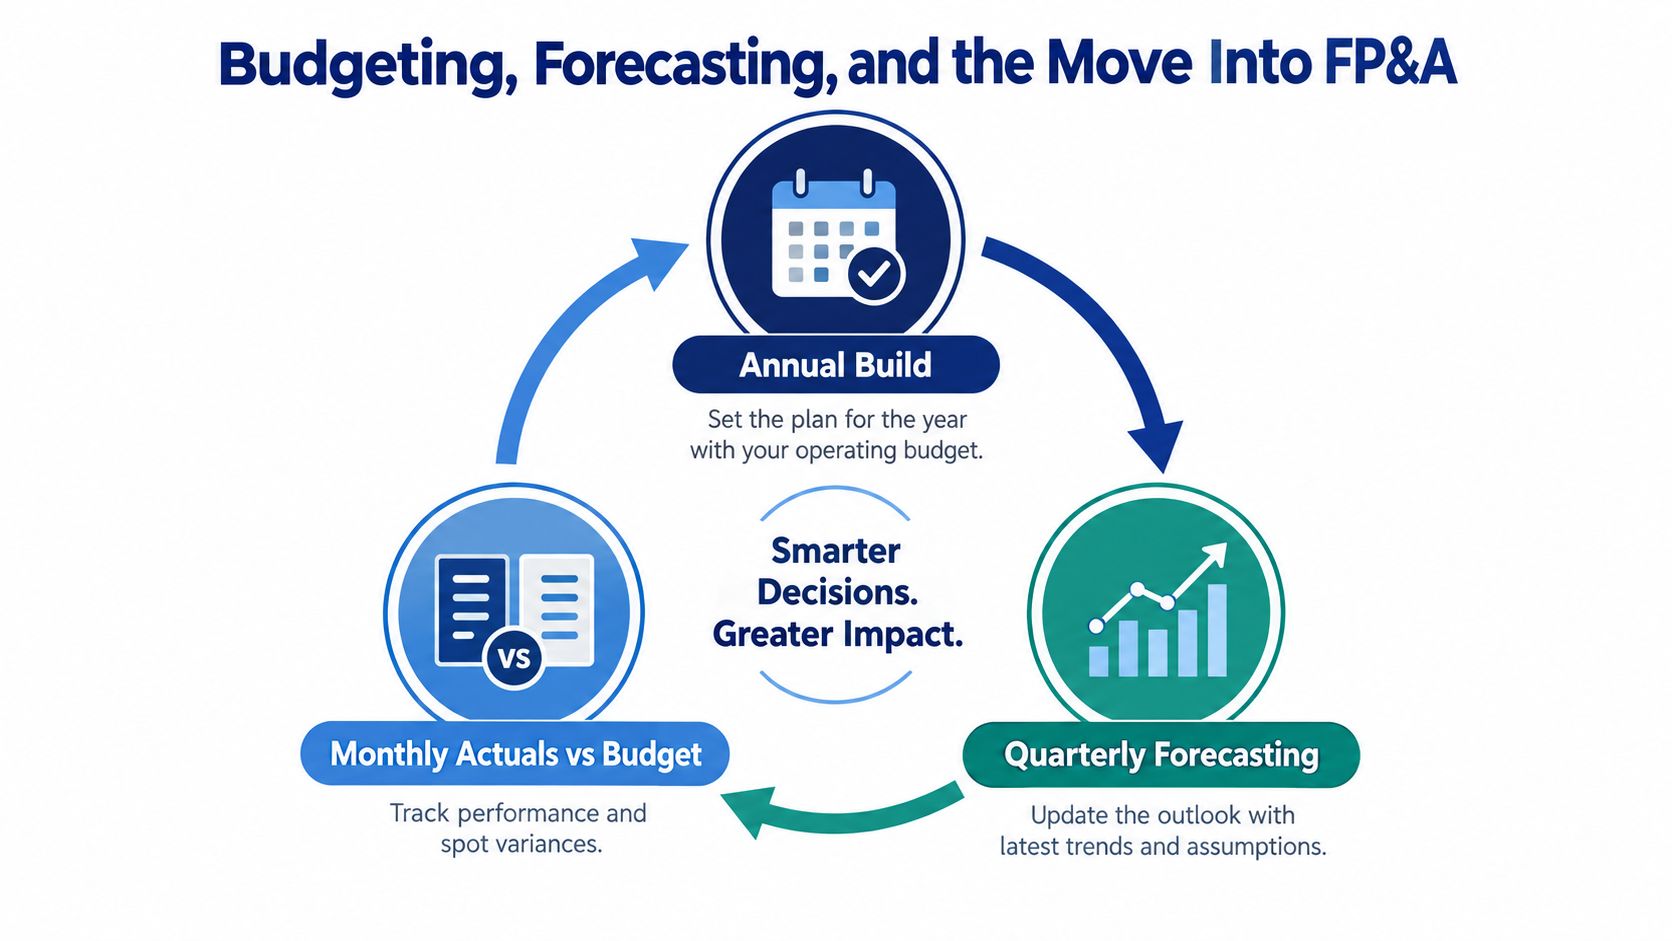
The division of labor matters:
A strong controller flags burn drift before it becomes a board surprise, challenges an optimistic collections assumption, and turns a deck chart into an operating decision. A lift-ready duty bullet is: “Own the 13-week cash forecast updated weekly, with variance commentary tied to AR aging, AP timing, and payroll.”
The classic startup mistake is skipping forecast cadence because close is too busy. That's precisely when the forecast becomes most valuable. If the controller is spending every available hour cleaning transactions, don't pile on a full FP&A function and pretend the work will happen at night.
Hire a dedicated FP&A analyst when recurring planning, KPI ownership, scenario modeling, and business-partnering consume enough time to compete with controllership. Until then, let the controller build a durable cadence, with the CFO deciding which scenarios deserve executive action.
The best controller I ever hired didn't just know debits and credits. They knew how to stop a small mistake from becoming a team tradition.
That means setting a review cadence for staff accountants and bookkeepers, inspecting reconciliations, and making errors safe to surface. A controller who only checks whether work arrived on time will miss the silent failures. A controller who reviews the logic, evidence, and follow-through builds a team that gets more reliable instead of merely more exhausted.
Audits reveal the difference quickly. One controller I inherited had a QuickBooks file carrying three years of uncoded transactions. Another let an audit drag for weeks because PBC items arrived without signatures and nobody owned the request list. Good audit liaison work means preparing PBC materials, routing requests without burning engineering time, answering auditor questions directly, and addressing the management letter instead of hiding it in a drawer.
Tax coordination has its own traps. The controller works with outside preparers on sales-tax nexus, 1099 workflows, income-tax support, and year-end handoff timing. They don't need to replace the tax adviser, but they do need to deliver complete schedules early enough for the adviser to work properly.
Vendor management is equally unglamorous. Review Bill.com or Ramp terms, maintain a clean vendor master, eliminate zombie subscriptions, and challenge invoices that don't match the approved service. Finance software is not a savings strategy if nobody cancels the tools the prior bookkeeper forgot.
A controller's quality shows up in the tasks nobody put in the offer letter.
A controller dashboard should expose risk, not decorate the board deck. Track the close cycle, reconciliation completion, audit adjustments, AR health, accrual quality, transaction automation, and vendor-payment execution.
| KPI | Healthy Target | Warning Sign |
|---|---|---|
| Close cycle | 5 to 7 business days for SMBs, with tighter timing as startups scale | The close creeps past 10 business days or deadlines keep moving |
| Audit-adjusting entries | Low and explained relative to net income | Repeated material adjustments or unexplained changes |
| Days sales outstanding | Stable against the company's collection pattern | DSO rises while AR aging gets older |
| Accrual-to-cash variance | Small, explainable, and reviewed | Accruals routinely reverse into surprises |
| Auto-coded transactions | Rising share of routine transactions with human exception review | Staff still codes repetitive activity manually |
| On-time vendor payments | Consistent against agreed terms | Late fees, supplier complaints, or rushed approvals |
| Reconciliations | Complete, reviewed, and supported | Missing reconciliations or stale bank feeds |
| Flux response | Controller can explain material movement quickly | Nobody can answer a flux question in under ten minutes |
The numbers are signals, not trophies. A fast close with unsupported estimates is worse than a slightly slower close with evidence. A high auto-coding rate is worthless if the rules misclassify revenue or hide unusual spend.
For a broader quality framework that also applies to tax operations, review quality control metrics for tax teams. The founder-level red flags are simple: missing reconciliations, stale feeds, recurring unexplained adjustments, and a controller who learns about problems from the auditor.
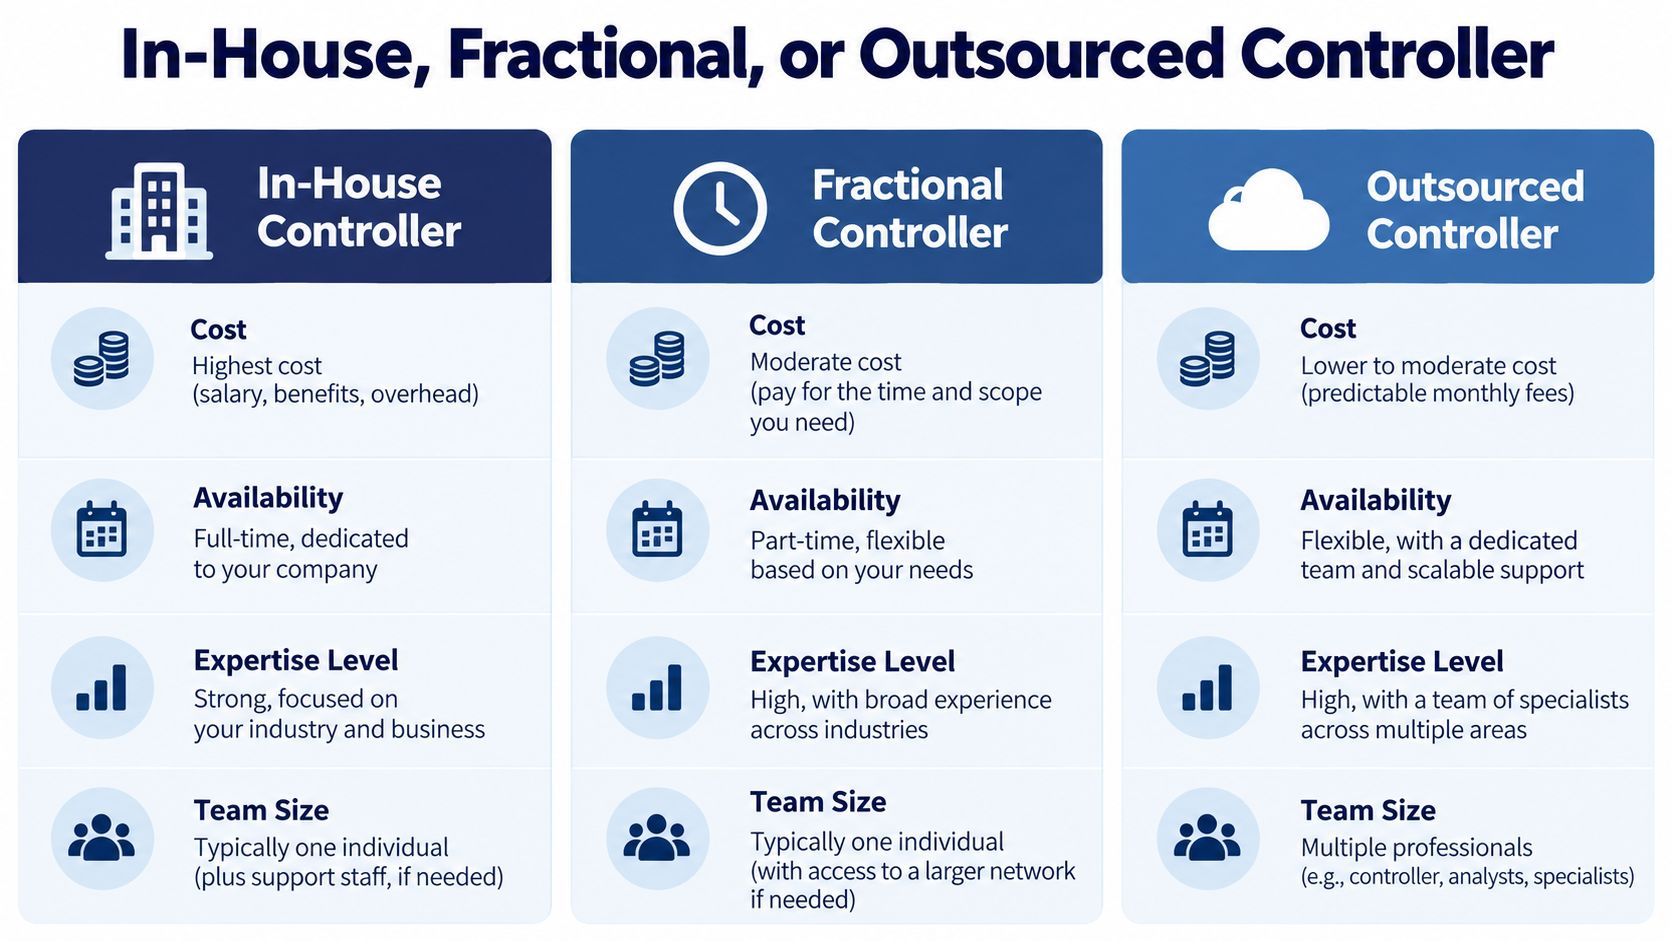
There are three sensible ways to buy controllership. The right answer depends on revenue, accounting headcount, complexity, and audit posture, not on whether an in-house title sounds more serious.
| Model | Best Fit | Cost and Capacity | Tradeoff |
|---|---|---|---|
| In-house controller | Companies above roughly $50 million to $100 million with three to five accountants | Fully loaded cost of $150,000 to $220,000 plus equity | Deep context and culture fit, but key-person risk |
| Fractional controller | Companies between $5 million and $50 million that need close quality and audit preparation | Typically $6,000 to $12,000 per month for 40 to 80 hours | Mature process experience, but the controller may juggle five clients |
| Outsourced accounting firm | Pre-Series A or companies below $5 million needing dependable close support | Usually $2,000 to $5,000 monthly | Lower cost, but firms rarely challenge the founder aggressively |
Those ranges are decision guides, not laws. A regulated, multi-entity company may need senior control earlier. A simple business with clean books may not need a full-time controller even after crossing a revenue threshold.
In-house gives you context. It also gives you one throat to choke and one person who can walk out with the institutional knowledge. Fractional controllers bring pattern recognition and process maturity, but availability can be constrained. Outsourced firms can deliver consistent transaction processing and close support, yet the service may remain reactive unless you explicitly require variance analysis, control ownership, and escalation.
For a practical overview of fractional accounting services, compare the promised deliverables against your actual close calendar. Don't buy “monthly bookkeeping” when you need reconciliations, GAAP judgment, audit PBC management, and a forecast.
The rule is straightforward: choose in-house for sustained complexity and leadership bandwidth, fractional for a growing company that needs controllership before a full-time executive, and outsourced for reliable accounting execution without strategic finance.
Automation should remove repetition, not remove judgment. Start with high-volume, low-judgment work: bank reconciliations, invoice coding, recurring journal entries, depreciation, and intercompany eliminations. Give the software a narrow lane, then make a human review exceptions.
Keep humans responsible for revenue recognition under ASC 606, lease accounting under ASC 842, contingent-liability assessment, audit liaison judgment calls, and sign-offs connected to Sarbanes-Oxley-style controls. A machine can identify an unusual entry. It shouldn't decide whether management's accounting judgment is defensible and then approve its own conclusion.
A practical rollout has three gates:
A fractional or outsourced controller paired with close software such as Ramp, Brex, Mercury, QuickBooks Online Advanced, NetSuite, FloQast, or Numeric often beats a junior in-house hire buried under spreadsheets. Companies with unusual workflows may need enterprise ERP system customization, but customization should follow process clarity, not compensate for its absence.
The controller remains the system orchestrator and control owner. Automation is useful when it creates cleaner evidence and faster exceptions. It's expensive theater when it merely produces more dashboards nobody reviews.
Use this as a starting point for a Series A to Series C startup or a $5 million to $50 million ARR SMB.
Objective: Own accounting operations, close integrity, GAAP reporting, internal controls, audit readiness, tax coordination, and a dependable cash and planning cadence. Report to the CFO and lead the accounting team.
Core duties: Own the close calendar, prepare financial statements, maintain reconciliations, manage revenue and complex accruals, coordinate audits and tax advisers, document controls, oversee AR and AP, and support forecasting.
Qualifications: Proven close leadership, GAAP depth, audit experience, judgment with estimates, and the ability to explain financial issues to non-accountants. Experience with QuickBooks Online Advanced, NetSuite, Bill.com, Ramp, or related systems is useful.
Ask candidates:
30-60-90 plan: In the first 30 days, audit the close, reconcile every balance-sheet account, and document the current state. By 60 days, stabilize the cadence, deliver the first clean monthly package, and tighten controls. By 90 days, hand off a working forecast model and present the first KPI dashboard.
Check references with former CFOs and direct reports. Reject candidates who can't explain their reconciliations, blame every prior error on “the system,” or confuse producing reports with owning the numbers.
HireAccountants helps US companies source pre-vetted accountants and finance professionals for bookkeeping, reconciliations, close support, and controller-related work, with full-time and part-time arrangements available. If you need to stabilize accounting controller duties before committing to a permanent hire, visit HireAccountants and compare candidates or support options for your finance function.
Let's simplify your finances today!