


64% of small business owners do their own bookkeeping, and most of those businesses are flying blind on cash flow. The cheaper option is usually not doing it yourself. It's building a financial system that tells you what's happening before the money gets tight.
I learned this the expensive way. A spreadsheet can look tidy while invoices sit unpaid, personal expenses contaminate business records, and a tax bill ambushes the bank account. Bookkeeping isn't data entry with a nicer name. It's the operating system behind hiring, pricing, borrowing, paying vendors, and deciding whether that “great opportunity” is affordable.
The right bookkeeping services for small business create visibility, controls, and usable reporting. The wrong provider sends you a polished profit and loss statement after the decisions have already been made. That's not financial management. That's archaeology.
The lie is simple: “I'll handle the books until the business is bigger.”
Plenty of owners believe bookkeeping takes a few quiet hours on Sunday. Then Sunday becomes month-end, month-end becomes tax season, and tax season becomes a frantic search for receipts while QuickBooks asks whether a payment was office supplies, owner's draw, or an ancient mystery.
The numbers explain why this habit is so common. 64% of business owners do their own bookkeeping, while about 30% of small businesses have an accountant and around 70% do not have one at all, according to small-business accounting statistics from BusinessDasher. The same source reports that 60% of small business owners feel they aren't knowledgeable enough about accounting, even as 64.4% use accounting software.
That combination is the trap. Software makes recording transactions easier, but it doesn't decide whether a transaction is categorized correctly, whether a bill should have been paid, or whether cash is about to disappear.
Founder rule: If you only open your books when someone asks for them, you don't have a finance process. You have a financial emergency drawer.
Doing the work yourself appears free because no vendor sends an invoice. The cost still arrives through missed deductions, duplicate expenses, slow reconciliations, late customer follow-up, and decisions made from stale numbers.
Bookkeeping also competes directly with revenue-producing work. Every hour spent cleaning a general ledger is an hour not spent selling, serving customers, improving delivery, or fixing the product. You may be saving cash while mortgaging your attention.
The better question isn't, “Can I categorize transactions?” You probably can. The better question is, “Can I maintain accurate records, review exceptions, reconcile accounts, preserve documentation, and turn the results into decisions every month?”
If the answer is no, outsourcing isn't an admission of defeat. It's a control decision. The owner should own the numbers, not necessarily the keystrokes.
You have three workable models. The old choice, "do it yourself or hire a full-time employee," leaves out the option most small businesses need.
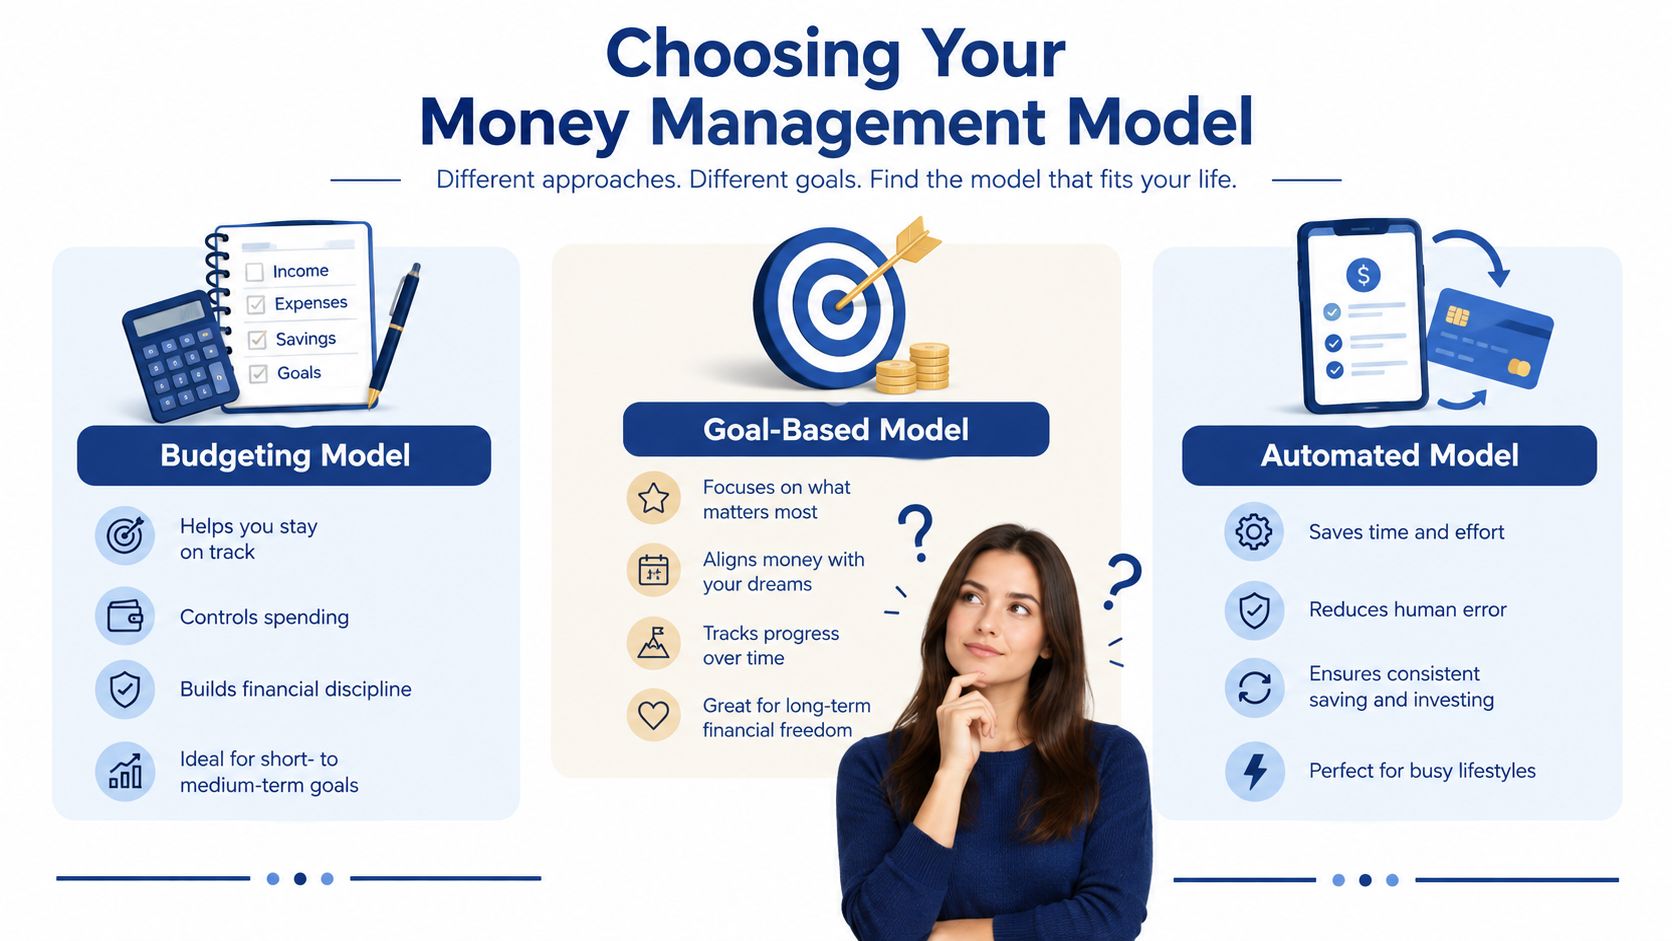
An employee gives you proximity. You can ask questions quickly, shape the workflow, and keep sensitive financial work close. You also become responsible for hiring, training, supervision, coverage during absences, software access, and performance management.
That model can make sense when transaction volume and operational complexity justify a dedicated finance seat. It makes less sense when the owner hires someone mainly to avoid paying for outside expertise, then spends months teaching that person the business and reviewing preventable errors.
Online bookkeeping subscriptions usually package recurring transaction work, reconciliations, and standard reports. They can provide a predictable process and a cleaner division of labor than DIY bookkeeping.
The limitation is context. A standardized service may tell you what happened without helping you decide why margins changed, whether pricing covers delivery costs, or which receivables deserve attention first. If your business needs interpretation, ask exactly who reviews the reports and how often you can speak with that person.
A dedicated outsourced bookkeeper can manage transaction coding, reconciliations, accounts payable and receivable, and recurring reporting. You retain decision authority while someone else maintains the machinery.
This is usually the strongest middle ground for a growing company. You get specialized labor without turning bookkeeping into another department to manage. If financing is part of the plan, clean books also support lender preparation. Owners comparing financing routes may benefit from reviewing the benefits of using an SBA broker alongside their bookkeeping model.
Choose based on the operating result you need:
| Model | What you gain | What can go wrong |
|---|---|---|
| DIY | Immediate control and low direct expense | Stale records, weak review, owner distraction |
| Subscription | Repeatable transaction processing | Limited business context and advisory depth |
| Outsourced specialist | Expertise, reporting, and workflow ownership | Poor results if scope and communication aren't defined |
The model matters less than the cadence. Books that close reliably and explain cash are useful. Books that merely exist are decorative.
Price objections are usually emotional before they're mathematical.
NerdWallet's pricing guidance says small businesses should expect to pay around $300 or more per month for bookkeeping, as outlined in its bookkeeping pricing guidance. A separate 2026 pricing guide places typical small-business bookkeeping at $500 to $1,200 per month for businesses handling about 150 to 400 monthly transactions.
Those ranges aren't contradictory. They describe different levels of volume, complexity, and service. Basic recording costs less than a reliable monthly close with reconciliations, reporting, payables, receivables, and review.
| Option | Direct cost pattern | What the owner still carries |
|---|---|---|
| DIY | No separate provider fee | Time, review, corrections, compliance organization |
| Part-time support | Flexible recurring expense | Scope management and continuity |
| Full outsourced service | Higher recurring fee | Provider oversight and decision review |
| Employee | Payroll and employment overhead | Management, coverage, training, and systems |
The cheapest line item can become the most expensive operating model. If you spend your evenings repairing categories, chasing missing documents, and reconstructing prior months, your business is paying you to do low-value work. Worse, you may be doing it inaccurately.
For a practical comparison of packages and service levels, use this guide to bookkeeping costs from Approved Lux Personal Assistant. Then compare every proposal against the actual deliverables, not the provider's favorite adjective.
A useful starting point is the HireAccountants bookkeeping services price list. Don't treat any published price as a promise. Treat it as a prompt to ask what transaction volume, reconciliations, reporting, cleanup, and communication are included.
The right fee buys more than categorized expenses. It buys faster answers. Can you afford to hire? Which clients owe cash? Did gross margin move because of pricing, delivery costs, or a classification error? If the service helps answer those questions before they become emergencies, it isn't overhead. It's operating infrastructure.
A bookkeeper who sends one annual profit and loss statement before tax filing isn't providing ongoing financial management. They're arriving at the scene with a mop.
Your agreement should define what gets done, when it gets done, who reviews it, and what happens when the books don't tie. If the provider can't explain the workflow in plain English, don't assume the work will become clearer after signing.
At minimum, ask for:
The reports matter because they prevent different kinds of bad decisions. The profit and loss statement shows operating performance. The balance sheet shows what the company owns and owes. The cash flow statement shows whether the bank account can support the plan.
Don't accept “monthly bookkeeping” as a complete answer. Ask when transactions are imported, when reconciliations begin, when exceptions reach you, and when final reports arrive.
You also need a document policy. Receipts, invoices, contracts, loan records, and payment confirmations should connect to the transaction they support. A number without evidence is just an ambitious rumor.
Practical rule: A deliverable isn't a report. A deliverable is a report you can use before the next important decision.
Finally, define access controls. The provider should use separate user permissions, protect banking information, and maintain a clear approval path for payments and vendor changes. Clean books without controlled access are still a risk.
The IRS doesn't care that your bookkeeping became difficult during a busy quarter. It cares whether you can support the income and deductions reported on your return.
The IRS says small businesses should generally retain records for three years, while employment tax records must be kept for at least four years, according to the IRS guidance on recordkeeping questions. The period depends on what the document supports, not on a universal “delete everything after tax season” rule.
That distinction matters. The IRS explains that records must be kept long enough to prove the income or deductions on a return, as described in its small-business recordkeeping guidance. Certain situations can require longer retention, including returns involving income understated by more than 25%, or claims involving bad-debt or worthless-securities losses.
A responsible bookkeeping system does three things:
CPA Australia's small-business control guidance recommends checking transaction dates, separating business and personal accounts, reconciling regularly to bank statements, restricting access to banking information, and using dual approval or multistep review for disbursements and vendor setup. Those controls stop bad entries upstream, where correction is cheaper.
Tax reporting also keeps changing. The cited industry guidance identifies a $2,500 1099-K reporting threshold for 2025 and a projected $600 threshold for 2026, so owners shouldn't wait for tax preparation to discover missing payment records. Keep the bookkeeping current and let your tax professional interpret how the rules apply to your situation.
The boring retention policy is cheaper than reconstructing a year from email attachments. Boring is underrated when the IRS is involved.
Modern bookkeeping shouldn't mean handing over a shoebox and hoping someone has strong wrists.
Automation handles repeatable work. People handle ambiguity, unusual transactions, approvals, and risk. That division is the point. The goal isn't to remove judgment. It's to stop spending judgment on routine matches that software can process consistently.
One independent benchmark reports that AI-assisted reconciliation can reduce reconciliation time by about 70%, taking 500 transactions from roughly 3.5 hours to about 1 hour. It also reports error rates below 0.5% for the AI-assisted workflow versus 1% to 8% for manual workflows, and a potential reduction in month-end close from 8.2 days to 3.5 days. Those figures come from the AI bank reconciliation automation benchmark.
Your provider should configure rules for recurring vendors, standard deposits, and known transfers. The system should then flag unusual amounts, duplicate-looking entries, unmatched transactions, and items that need documentation.
That creates a better monthly close. Routine work moves quickly, while a human reviews the transactions most likely to affect cash, taxes, fraud exposure, or management reporting.
Internal controls belong in the same design. The relevant AI bookkeeping automation research highlights controls such as limiting system inputs, separating personal and business accounts, checking dates, reconciling regularly, restricting bank access, and requiring multiple approvals for sensitive disbursements.
Automation without controls makes bad processes faster. A cloud platform with careless permissions is a digital version of leaving the office door open.
The broader direction is clear. A 2026 accounting automation roundup reports that 95% of accountants have adopted some form of automation, with common uses including payroll processing at 47%, accounts payable and receivable at 46%, and data entry or transaction processing at 43%, according to Dokka's accounting automation statistics.
If you want to map repetitive finance work before hiring, review this resource on accounting process automation. Then insist that automation supports a review process, not replaces one.
The cheapest candidate is often cheap because you're buying task completion instead of ownership.
Start with a short cleanup period. Give the candidate read-only access where possible, a representative set of transactions, your current chart of accounts, and a clear description of the decisions you make from your reports. Ask them to identify ambiguities rather than forcing every transaction into a category.
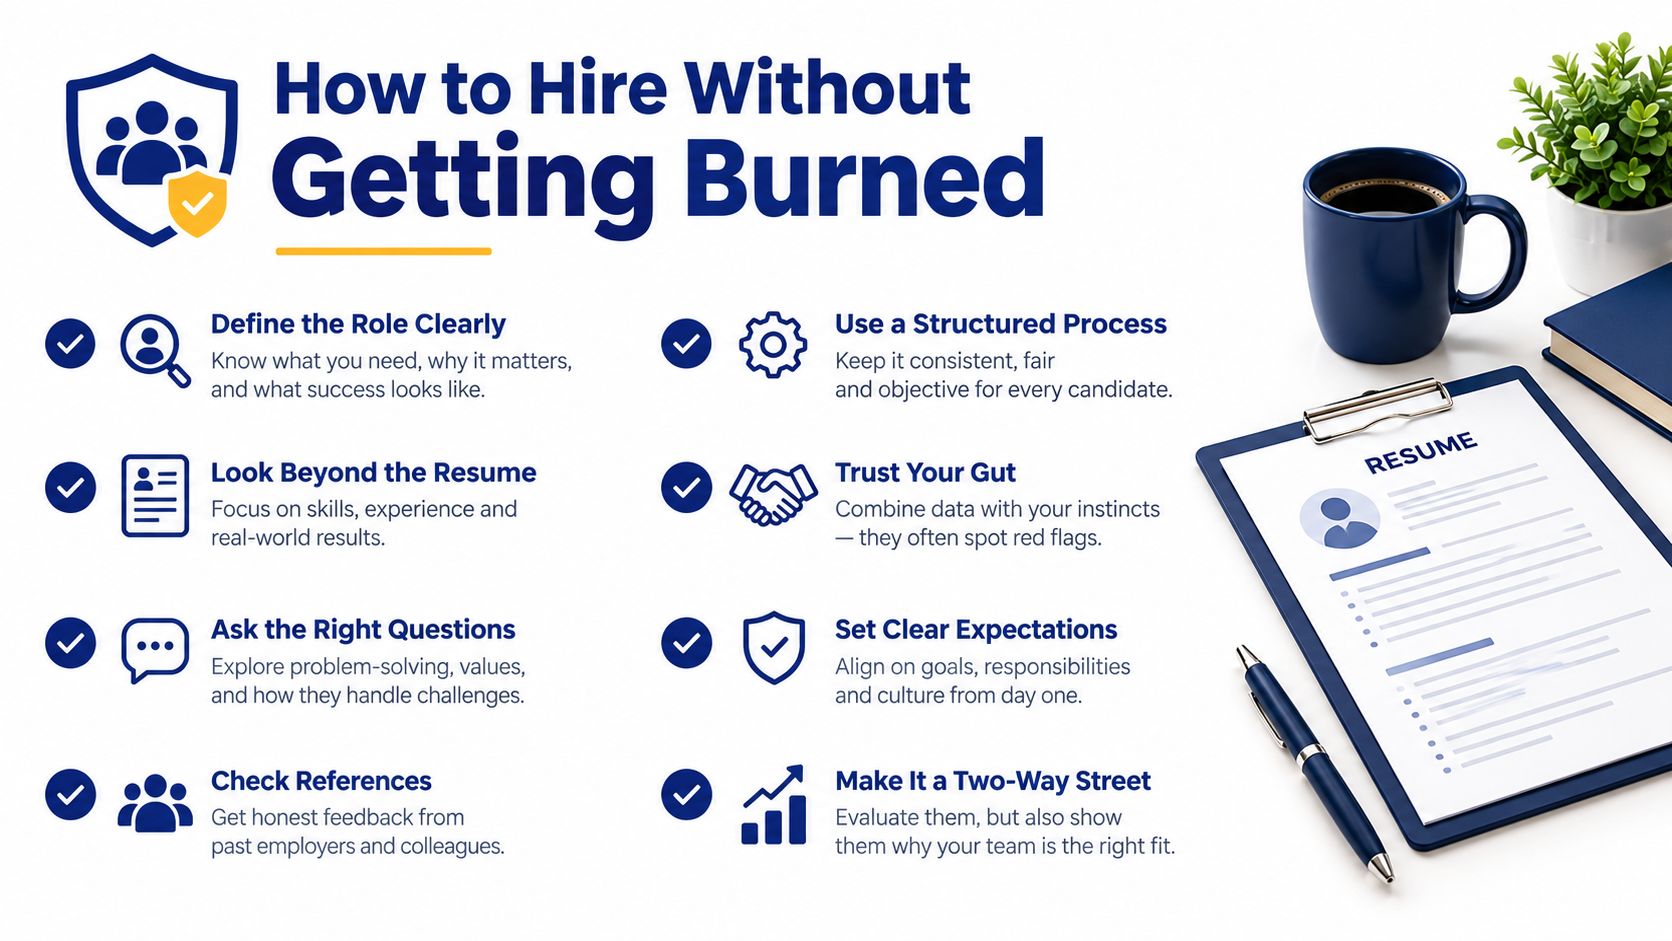
Technical competence is necessary. Communication determines whether that competence reaches you in time.
Ask candidates:
A competent candidate won't promise that every month will be painless. They'll explain where owner input is required, how long unresolved items can remain open, and which decisions belong with your CPA or tax adviser.
First, separate personal and business accounts. Next, gather bank statements, credit-card statements, loan documents, merchant reports, vendor bills, customer invoices, and prior financial statements. Then agree on the chart of accounts, reporting dates, approval limits, and the definition of a “closed” month.
Keep legal and financial administration organized too. An AI legal assistant for business owners can help with administrative questions, but it doesn't replace your accountant, bookkeeper, or attorney when professional judgment is required.
Use this guide on how to hire a bookkeeper to structure the search, then request references from businesses with similar transaction patterns. A reference should be able to describe responsiveness, cleanup ability, and whether the provider explains the numbers without hiding behind accounting jargon.
Give the relationship a defined review point after the first completed close. Keep the provider if the books are cleaner, questions are answered faster, and reports lead to better decisions. Don't keep them because changing providers feels annoying. That is how expensive mistakes gain tenure.
Bookkeeping is the central nervous system of the company. You don't need to stare at it all day, but you do need reliable signals from it.
The common misconception is that bookkeeping exists mainly for tax filing. Tax readiness matters, but it is the floor. A functioning finance process tells you whether customers pay on time, whether expenses are drifting, whether a new hire fits the cash plan, and whether growth is creating profit or merely creating more invoices.
Ask for reports that support decisions, not reports that decorate a shared drive.
The right provider also knows the limits of bookkeeping. A bookkeeper maintains and interprets operational records. Your CPA handles tax filing and specialized tax advice. Your attorney handles legal questions. Don't ask one professional to impersonate all three because the monthly fee feels tidy.
Outsourcing isn't automatically smart. A bad outsourced relationship can create its own mess. But doing everything yourself isn't automatically frugal either. The correct test is whether your current process produces accurate, timely, decision-ready information without consuming the founder's best working hours.
Choose in-house when you need constant proximity and can manage the function properly. Choose a subscription when recurring transaction work is your main need. Choose a dedicated outsourced professional when you need someone to own the close, challenge incomplete records, and turn financial activity into operating insight.
Don't wait for the next tax deadline to find out whether your books work. Review the last completed month, list every unresolved exception, and ask what decision you couldn't make because the numbers weren't ready. That list is your hiring brief.
HireAccountants helps US companies find pre-vetted accountants and finance professionals, including remote bookkeepers for recurring transaction and reconciliation work. Visit HireAccountants to compare qualified support options and start building a finance process that gives you clearer books, faster answers, and fewer expensive surprises.
Let's simplify your finances today!