


The popular advice is simple: buy QuickBooks, keep the books yourself, and hand everything to your CPA at tax time. That advice works right up until your company becomes complicated enough to need accurate information before tax season. Then the “cheap” option turns into late nights, unexplained balances, missed filings, and decisions made with financial data you don't trust.
Good bookkeeping services in the USA aren't about typing transactions into software. They're about building a dependable monthly process around reconciliations, documentation, exception handling, and reporting. For many startups and small businesses, the practical answer isn't a full-time local hire. It's a properly scoped remote finance professional who works in your time zone, understands US accounting workflows, and knows where bookkeeping ends and CPA or legal work begins.
You didn't start a company to categorize Stripe payouts at 2 AM. Yet plenty of founders keep doing exactly that because software makes bookkeeping look easier than it is.
QuickBooks Online can import transactions, suggest categories, and generate reports. It can't reliably decide whether an unusual payment is a prepaid expense, an owner distribution, a loan repayment, or a software charge that belongs in a different department. It also won't chase a missing receipt, investigate a reconciliation difference, or tell you that your payment processor settlements don't match your sales reports.
A recent survey found that more than two-thirds of US small-business owners still handle bookkeeping themselves, while bookkeeping remains a major challenge for 65% of small businesses and 40% report financial errors associated with manual bookkeeping. Those figures come from CNBC Select's overview of DIY bookkeeping. The issue isn't founder intelligence. It's that bookkeeping becomes an operational system long before it becomes an obvious hiring priority.
Revenue alone doesn't tell you when to delegate. Workload, risk, and reporting demands do.
You should stop treating bookkeeping as a weekend task when several of these conditions appear:
Practical rule: Delegate the work that requires repetition and judgment first, not the work that merely feels annoying.
A messy ledger rarely fixes itself. Unreconciled accounts make reports unreliable, unreliable reports delay decisions, and delayed decisions force founders to operate by bank balance and instinct. That might get you through a quiet month. It won't support hiring, fundraising, inventory planning, or a serious tax handoff.
The smart move is often a recurring close process rather than a traditional full-time accounting department. A part-time or fractional bookkeeper can maintain the ledger, reconcile accounts, document exceptions, and prepare a clean package for your CPA. If you're evaluating the broader business case, this practical guide to the benefits of outsourcing accounting services is a useful complement to the workload test.
Don't wait for tax season to discover that your books need surgery. Tax season is when your CPA needs usable records, not when you should begin reconstructing them.
Once DIY stops working, three hiring paths usually appear. You can hire locally, outsource to a firm, or build a remote relationship with a finance professional in Latin America. Each can work. Each can also become an expensive lesson if you buy the wrong level of support.
A local employee gives you proximity and direct control, but the fully loaded cost includes recruiting, payroll administration, benefits, management time, equipment, and coverage when that person is unavailable. A local accounting firm offers process and oversight, yet many firms package routine bookkeeping with services you don't need or route day-to-day work through junior staff.
A freelancer can be flexible and affordable, but availability becomes a serious concern around month-end close. If the person disappears, takes on too many clients, or lacks experience with your payment platforms, you inherit the cleanup.
The labor market explains why these choices feel crowded. The Bureau of Labor Statistics reports that bookkeeping, accounting, and auditing clerks held approximately 1.5 million jobs in 2025. The occupation had a median annual wage of approximately $49,210 in May 2024, while employment is projected to decline by 6% from 2024 to 2034 as software automation reduces demand for routine tasks. The work isn't disappearing. Routine entry is being squeezed, while reconciliation, review, exception handling, and reporting become more valuable.
| Talent Model | Typical Cost | Scalability | Best For |
|---|---|---|---|
| Local employee | Highest total employment overhead | Moderate, tied to hiring capacity | Businesses needing daily onsite collaboration |
| Local accounting firm | Premium service pricing | Moderate, depending on team coverage | Owners wanting bundled accounting and tax support |
| Independent freelancer | Variable hourly or project pricing | Limited by one person's availability | Simple books with predictable transaction patterns |
| Remote LATAM professional | Flexible part-time or full-time arrangement | Strong when supported by a vetted talent pool | Startups and SMBs needing US-time-zone execution |
The remote LATAM model makes sense when the role is clearly defined and communication matters more than physical proximity. English-fluent professionals working in US time zones can attend close meetings, resolve exceptions during your workday, and collaborate inside the same cloud systems. That doesn't remove the need for controls. It makes those controls easier to operate consistently.
A remote bookkeeper isn't a shortcut around management. They're a way to spend management time on review and decisions instead of transaction chasing.
The model also requires credential clarity. A bookkeeper, enrolled agent, CPA, and tax preparer don't carry the same responsibilities, so founders should compare EA and preparer credentials before assigning tax-related work. For companies that want a remote team rather than a single point of failure, remote bookkeeping services can provide a more structured path to recurring coverage.
“Monthly bookkeeping” is not a scope of work. It's a label vendors use for very different deliverables.
At the basic end, bookkeeping may mean importing transactions, categorizing expenses, and reconciling bank accounts. That can suit a straightforward business with one operating account and limited payment activity. A growing company usually needs more: credit-card reconciliation, accounts payable and receivable tracking, payroll coordination, accrual entries, close procedures, and management reporting.
The right question isn't “How much does bookkeeping cost?” Ask, “What will be complete, reviewed, and delivered by the close deadline?”
A solo consultant may need cash-basis transaction coding, bank reconciliation, and a clean year-end package. An e-commerce company needs settlement reconciliation, refunds, chargebacks, merchant fees, inventory purchases, and sales-tax tracking. A SaaS company may need deferred revenue schedules, prepaid expenses, accruals, and recurring revenue reporting.
A useful scope should identify:
Bookkeeping doesn't automatically include financial planning and analysis, legal advice, tax representation, or every compliance filing. One frequently missed obligation is Form 8300. The IRS explains that businesses receiving more than $10,000 in cash, either in one transaction or in two related transactions, must file the form. Your provider should flag relevant information and establish an escalation path, but don't assume ordinary transaction entry handles the entire compliance obligation.
Before signing, ask the provider to answer these questions in writing:
A cheap provider that produces clean-looking ledgers without evidence, review, and reconciliation isn't cheap. It's deferred risk wearing a nice dashboard.
Your bookkeeper is only as reliable as the workflow around them. Give someone a bank feed, a vague scope, and a shared folder full of unlabeled receipts, then act surprised when month-end becomes archaeology.
Build the stack around an auditable transaction-to-document chain. The IRS permits businesses to use any recordkeeping system that clearly shows income and expenses, but the system must summarize transactions in journals or ledgers and preserve supporting evidence. Electronic records face the same standard as paper records, they must be complete, accurate, and accessible. The IRS recordkeeping guidance lays out that foundation.
Use a controlled capture process for invoices, receipts, bills, deposit records, and payment-processor statements. Assign consistent file names and connect documents to transactions wherever your accounting system supports it. A bank feed tells you money moved. The source document tells you why.
For e-commerce, map the full settlement chain:
For SaaS, add subscription billing, failed payments, credits, deferred revenue, and prepaid expenses where applicable. The goal is not a clever chart of accounts. The goal is a reviewer being able to trace a material balance back to primary evidence.
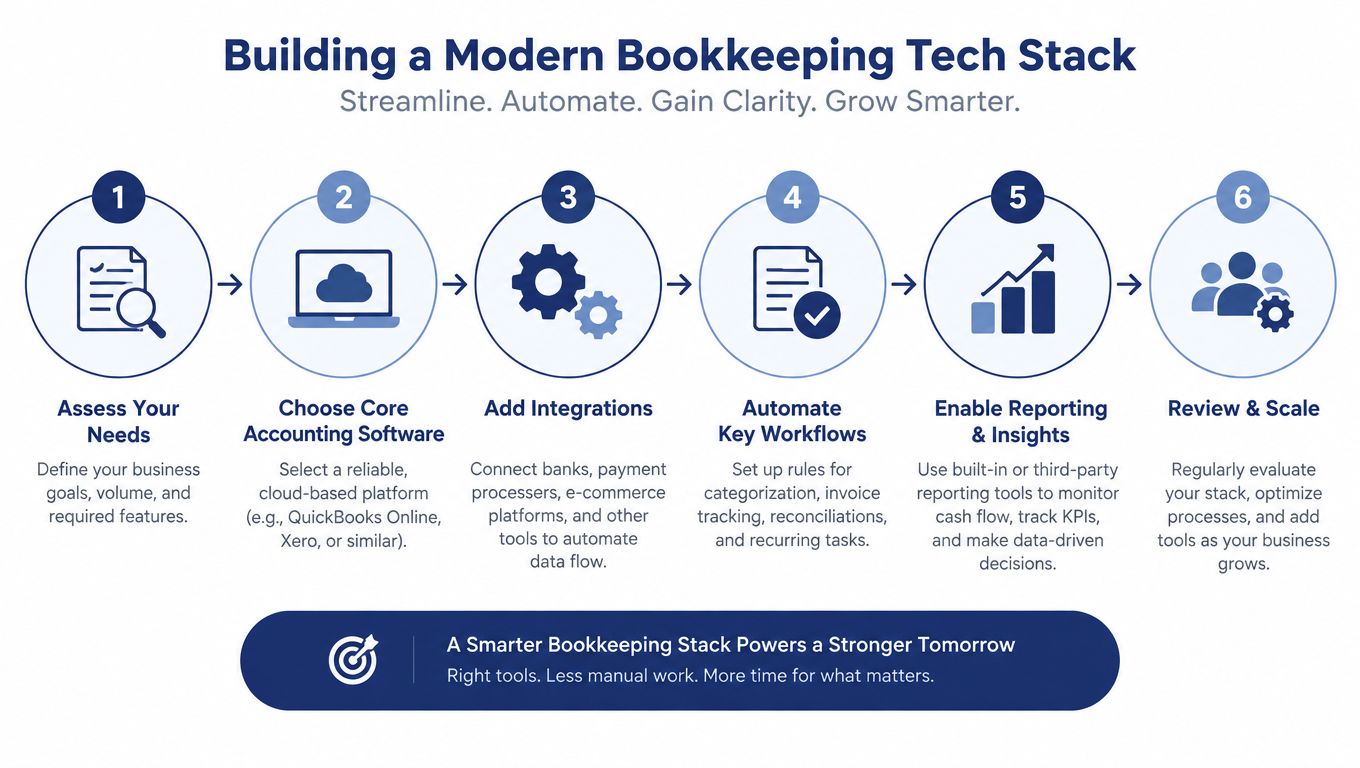
Automate imports and recurring entries, but keep human review for unusual transactions, reconciliation breaks, accruals, refunds, and classification changes. Use role-based access, approval workflows, encrypted cloud storage, automated backups, and exportable ledgers. If you're comparing accounting platforms and adjacent automation, this resource on AR automation for your firm offers useful context for evaluating how receivables work fits into the wider stack.
Retention needs its own policy. The IRS generally suggests retaining business records for three years, while employment-tax records must be kept for at least four years, according to its small-business recordkeeping guidance. Asset records may need to remain available while they support basis and depreciation information, so a single blanket deletion rule is lazy and risky.
Document retention by record type, owner, retention period, and disposal approval. Backups aren't decorative. They protect computerized records when hardware fails, staff leave, or a platform migration goes sideways.
A polished resume can hide a weak close process. Ask candidates what they do when the numbers don't tie, because routine data entry tells you very little about financial judgment.
Start by defining the role in operational language. “Bookkeeper” is too broad. Specify the accounting platform, bank and card accounts, payment processors, expected close date, reporting package, payroll coordination, industry requirements, and who owns tax decisions.
Use a practical interview rather than a vocabulary quiz. Ask:
Strong candidates explain their process, not just the final category. They talk about evidence, materiality, approval, documentation, and review.
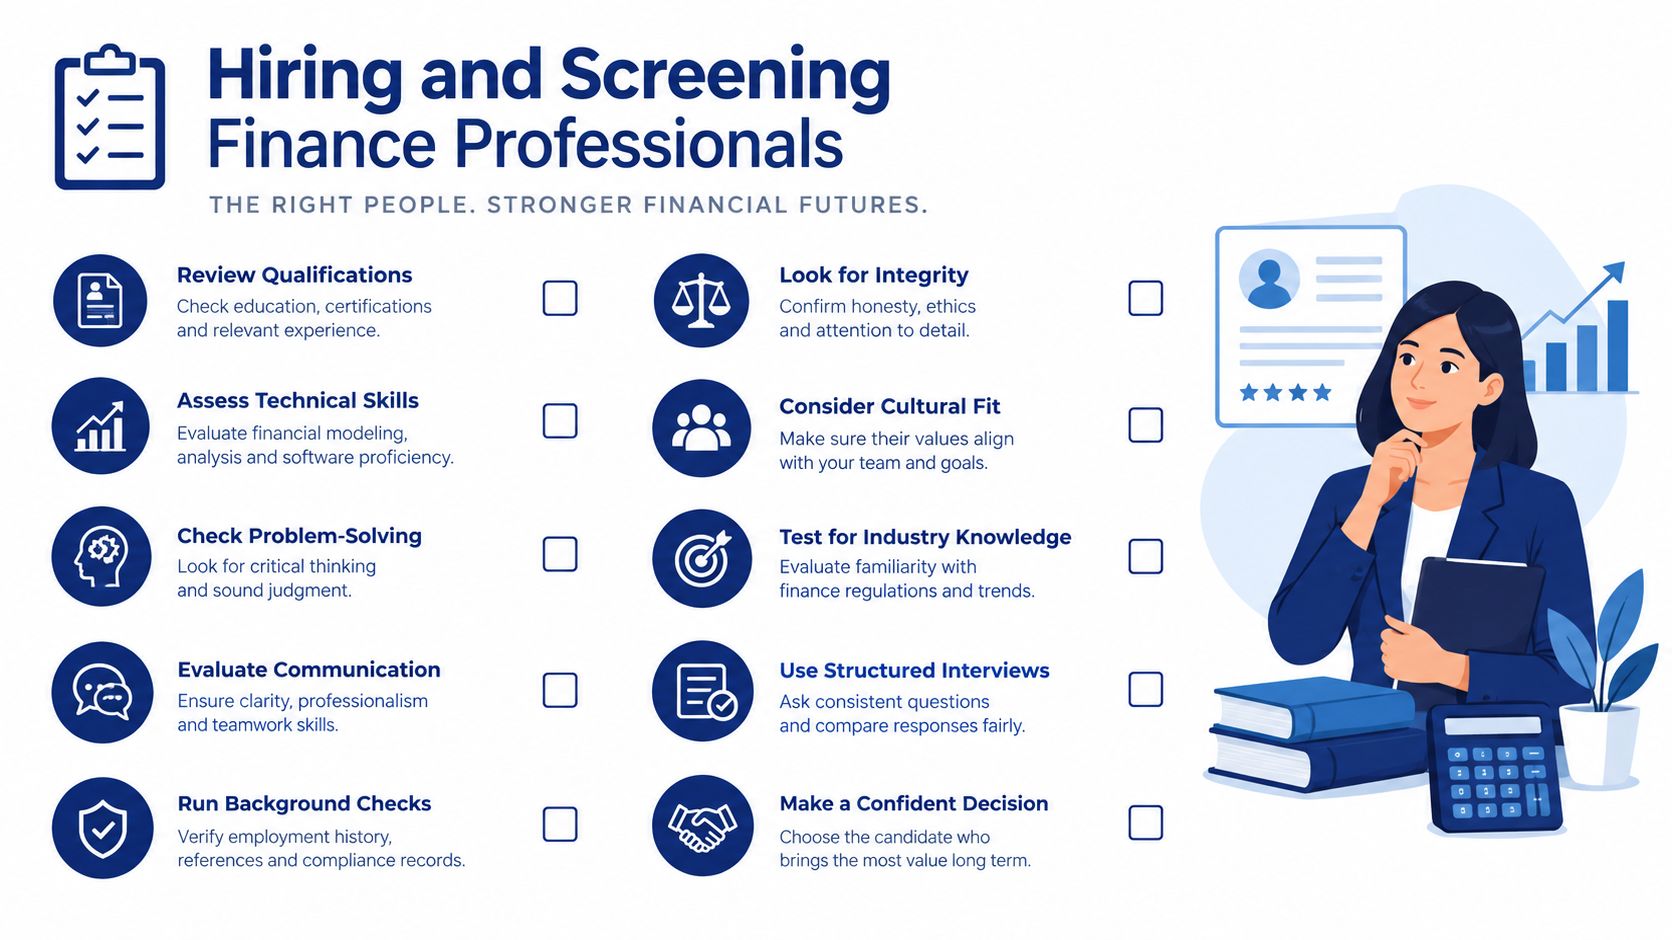
Ask for a short paid test using sanitized transactions. Test bank reconciliation, a payment-processor settlement, an unusual expense, and a month-end adjustment. Watch how the candidate documents assumptions and asks questions. Speed matters, but unexplained speed is just a future cleanup bill.
Check software familiarity directly. QuickBooks Online, Xero, Stripe, Shopify, Gusto, Bill.com, and spreadsheet workflows all require different habits. Confirm whether the candidate has worked with the tools your company uses, not merely listed them on a profile.
Communication matters just as much as technical accuracy for remote work. Ask how they report unresolved items, what their weekly update looks like, and how they handle a blocked task when the owner is unavailable. A candidate who waits in silence for three days isn't independent. They're invisible.
For a structured hiring route, founders can review how to hire a bookkeeper and turn the role into a repeatable screening process. HireAccountants is one option that connects US companies with pre-vetted finance professionals, including remote bookkeeping talent.
Let's talk about money without pretending every bookkeeping role has the same price.
You may encounter hourly freelancers, fixed-fee monthly packages, per-transaction pricing, part-time employees, full-time employees, or fractional teams. Hourly pricing can work for cleanup projects, but it becomes uncomfortable when the monthly invoice rises with every exception. Fixed monthly pricing is easier to budget, provided the scope defines transaction volume, accounts, reporting, close timing, and cleanup work.
The traditional US employee model carries more than wages. You also manage recruiting, payroll, benefits, equipment, supervision, absences, and replacement hiring. A local firm shifts some of that burden away from you, but you may pay for senior oversight while routine work happens elsewhere.
Remote Latin American talent can reduce the cost of building recurring bookkeeping capacity while preserving overlapping US working hours and English-language communication. The important comparison isn't a mythical “cheap bookkeeper” against an expensive CPA. It's a defined operating role against the total cost of local employment or a premium outsourced package.
Use a simple model:
Monthly finance cost = hours required × rate + software and management overhead + cleanup or review costs.
Then compare that number with the cost of delayed reporting, founder time, and corrective work. A low hourly rate doesn't win if the person needs constant instruction or leaves reconciliations unresolved. A higher rate can be rational when the professional closes quickly and reduces review work.
The savings should fund something useful, not disappear into a larger pile of subscriptions. Put the reclaimed cash toward inventory, customer acquisition, product development, or a tax reserve. Administrative savings only matter when they improve the company's operating choices.
Pay for the level of control you need, not the illusion of local proximity.
Nearshore talent isn't a substitute for a CPA, controller, or attorney when those professionals are required. It is a practical way to cover recurring execution, especially when a business needs part-time support rather than a full-time internal department.
No. Give the new provider the mess, but describe it accurately.
Separate historical cleanup from ongoing bookkeeping in the scope and pricing. Provide bank statements, credit-card statements, payment-processor reports, payroll records, tax returns, loan documents, and prior reconciliations. The provider should identify the opening-balance problem, list unresolved items, and explain which assumptions require CPA approval.
A cleanup project without documentation just creates a prettier version of the same problem.
Yes, but don't hand over more access than the role needs. Use an accounting integration or limited user permissions where available, keep payment approval separate from transaction recording, and require owner approval for transfers, refunds, vendor creation, and unusual disbursements.
Remote work increases the importance of access controls, not the inevitability of risk. Review user permissions regularly and remove access immediately when someone leaves the engagement.
Treat the CPA handoff as a monthly habit, not an annual emergency. Your bookkeeper should maintain organized reconciliations, supporting documents, fixed-asset information, loan records, payroll reports, and explanations for unusual balances.
Your CPA handles tax positions, filings, and professional tax advice. Your bookkeeper prepares reliable records and flags issues. The owner still needs to approve business decisions and answer questions about transactions. Clear ownership prevents the classic tax-season game of forwarding a mystery spreadsheet with “hope this helps” in the subject line.
At minimum, define a close checklist, a deadline, and an exception report. The checklist should cover bank and card reconciliations, payment-processor settlements, payroll, accounts payable and receivable, missing documentation, balance-sheet review, and delivery of agreed reports.
Don't judge the provider by how quiet they are. Judge them by whether the books close on schedule, exceptions receive answers, and every important balance has evidence behind it.
Often, yes. A company with predictable activity may need recurring reconciliation and reporting rather than a full-time employee. A multi-entity business with heavy billing, inventory, payroll, or investor reporting may need broader coverage.
Start with the workload and control requirements. Increase capacity when the close slips, exceptions accumulate, or management reporting becomes unreliable. Hiring a full-time person just to preserve a flawed process is an expensive way to avoid redesigning it.
HireAccountants connects US companies with pre-vetted accountants and finance professionals, including remote bookkeepers who can support reconciliations, transaction recording, and month-end close. Visit HireAccountants to define the role, compare qualified talent, and stop making your founder's calendar carry the bookkeeping department.
Let's simplify your finances today!