


Most advice on why hire a CPA starts in the wrong place. It tells you a CPA will “help with taxes,” which is technically true and about as useful as saying a surgeon “works with bodies.” The question is what problem you're paying to solve.
Most accounting work doesn't require a CPA. A capable bookkeeper can reconcile accounts, track payables and receivables, process routine payroll, and keep QuickBooks from becoming a digital junk drawer. But three jobs change the economics completely: representing you before the IRS, producing audit-level financial statements, and designing controls that protect the value of the business.
Hire a CPA for those jobs. Don't hire one to spend premium hours coding receipts. That's how founders end up paying surgeon prices for spreadsheet sweeping.
A CPA isn't merely a bookkeeper with a fancier business card. The credential matters because it allows for work that carries legal authority, professional standards, and outside-party credibility.
The three CPA-only jobs are straightforward:
Represent you before the IRS. A CPA can represent clients with unlimited practice rights in audits, collection matters, payment disputes, and appeals. The IRS credential overview explains that CPAs, attorneys, and enrolled agents hold this broad authority, while ordinary preparers don't.
Issue audited or reviewed financial statements. A CPA can perform an audit or review under recognized professional standards. An audit examines financial statements under generally accepted auditing standards and ends with an opinion about whether those statements conform to GAAP or another accounting basis, as described in the Iowa professional standards rule.
Build and evaluate internal controls. A CPA can design control systems, assess weaknesses, support forensic accounting work, and help management produce financial information that lenders, investors, boards, and buyers can scrutinize without immediately reaching for aspirin.
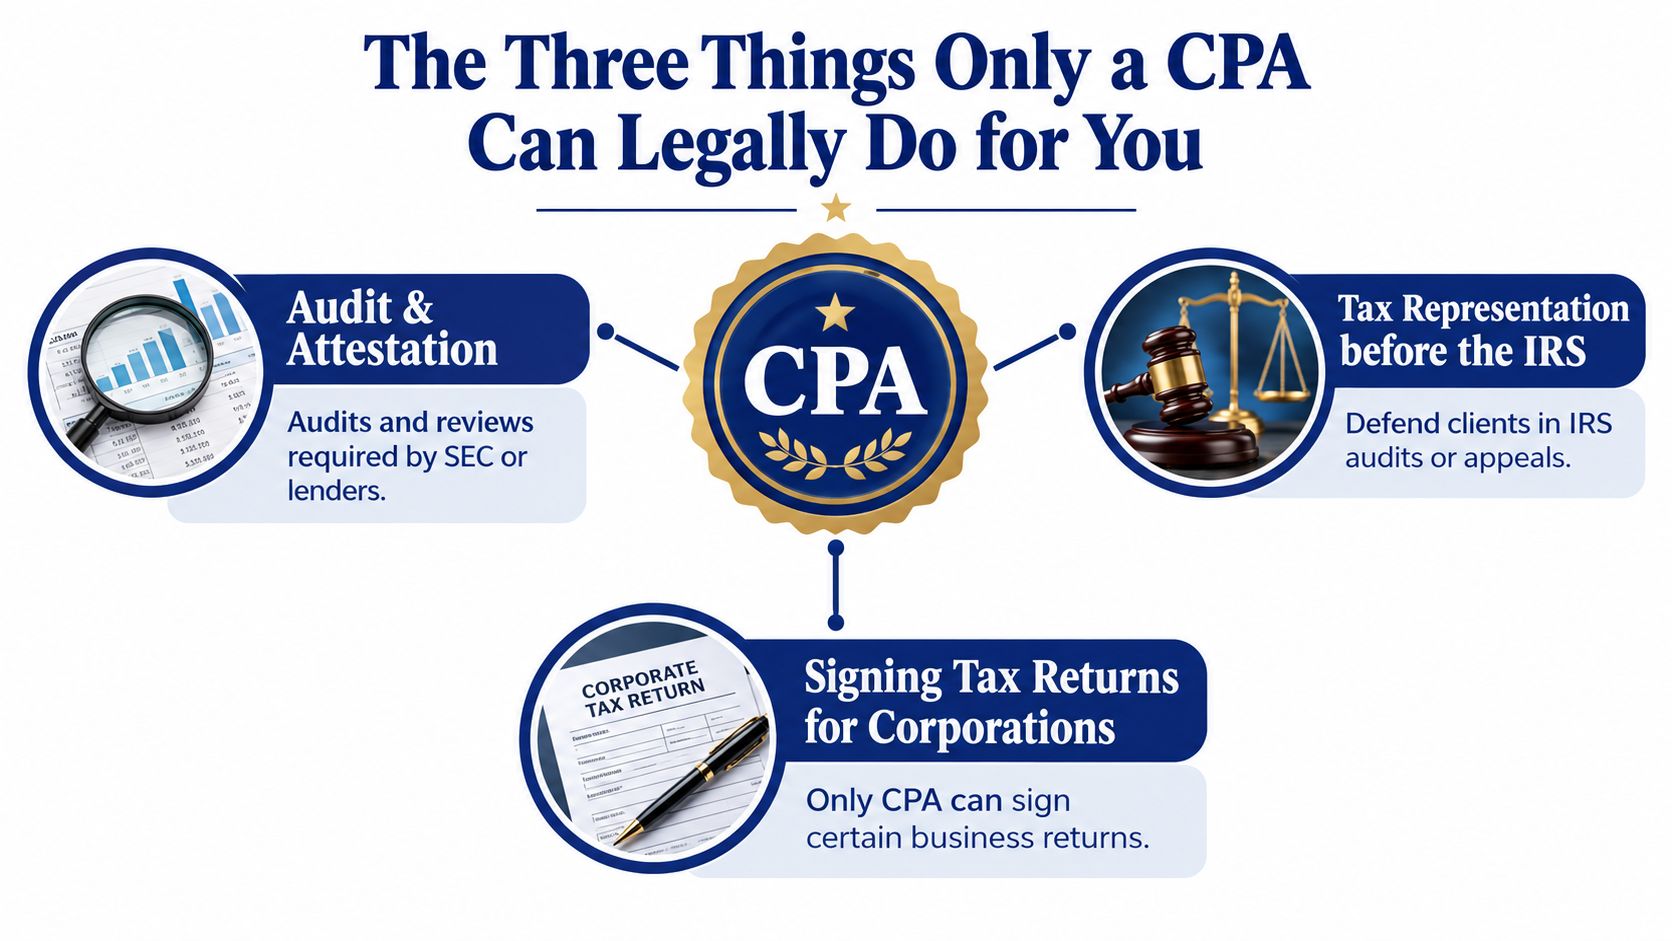
The practical rule: Use a bookkeeper for execution. Use a CPA when the numbers need authority, judgment, or a defense attorney's posture.
The credential doesn't make every CPA brilliant. It does create a legal threshold for work that affects tax disputes, financial statement assurance, and enterprise risk. State requirements vary, so founders should check the CPA requirements by state before assuming a person's title tells the whole story.
That distinction prevents two expensive mistakes. You won't pay CPA rates for data entry, and you won't send a bookkeeper into a situation where only a licensed professional can legally stand beside you.
The CPA license is deliberately difficult to obtain. Candidates must pass the Uniform CPA Examination, and state boards control the license. The IRS explanation of CPA qualifications confirms that CPAs are licensed by state boards of accountancy, the District of Columbia, and U.S. territories.
Behind the license sits formal education, supervised experience, examination, and continuing professional education. In many jurisdictions, candidates complete 150 semester hours before licensure, often through a master's degree or additional undergraduate accounting coursework. The exam covers four sections, and the licensing process remains state-specific.
That training matters because accounting errors rarely arrive wearing a name tag. They hide in revenue timing, related-party transactions, stock compensation, debt covenants, tax elections, and estimates that look harmless until a lender or buyer asks a very precise question.
A CPA has unlimited practice rights before the IRS. That means the CPA can handle any taxpayer, any IRS office, and any tax matter, including audits, collections, payment issues, and appeals. A bookkeeper may prepare records or help assemble documents, but that doesn't give them a legal seat at the table.
The IRS also says taxpayers generally have the right to suspend an interview and consult a representative such as a CPA. With a valid power of attorney, the CPA can act on the taxpayer's behalf, as explained in the IRS guidance on retaining representation.
That difference becomes painfully obvious when a notice arrives on a Friday afternoon. One person can interpret the issue, communicate with the agency, and manage the response. The other can tell you where the PDF is.
Internal financial reports are useful management tools. They aren't the same thing as an audit or review performed under professional standards. When a CPA signs an assurance report, the report carries a level of professional responsibility and credibility that outside users can evaluate.
Banks, investors, boards, and acquirers don't need a pretty spreadsheet. They need financial information prepared for scrutiny. A CPA's work can support letters and reports that those parties rely on when they decide whether to lend, invest, govern, or buy.
For founders building a finance stack, a practical Credit for Startups accounting guide can help with the software and recordkeeping layer. Just don't confuse a clean accounting platform with CPA-level judgment.
The credential is not a guarantee of quality. It's a legal and technical threshold. The moment a CPA signs, represents, or takes responsibility for high-stakes financial work, the business gains capabilities that an unlicensed preparer can't imitate with enthusiasm and a fresh Excel template.
A non-CPA usually doesn't become expensive because the hourly rate is high. They become expensive when the business reaches a problem their role wasn't built to solve.
The first warning sign is tax complexity across states or countries. Nexus, apportionment, registrations, and filing obligations can turn a seemingly simple operation into a thicket of exposure. A bookkeeper may accurately record sales while missing the tax consequence of where those sales occurred. A CPA can analyze the position, plan the filings, and help defend the conclusion.
The second moment arrives during investor due diligence. Internal reports may be perfectly adequate for running the company and still fail an investor's review. If the financials lack consistent policies, supporting schedules, or defensible revenue treatment, the founder may need to rebuild the reporting package while the deal sits on the runway with its engine running.
The cheap option is only cheap while nothing complicated happens.
The third moment is an IRS notice, audit letter, collection matter, or state levy. A founder who has treated tax preparation as a filing transaction may suddenly need representation. The IRS rules on CPA qualifications make the boundary clear. A CPA can represent the client broadly; a basic preparer can't assume that authority.
Fourth comes the control problem. Weak approvals, shared access, commingled funds, sloppy revenue recognition, and unsupported expenses create opportunities for fraud and error. The CPA's value here isn't posting transactions. It's designing a system that separates duties, documents approvals, reconciles balances, and detects problems before they become a board meeting.
Public-company evidence shows why that work deserves respect. One industry analysis found adverse internal-control assessments exceeded 26% of filers in 2021 and remained above 15% in 2024, according to Baker Tilly's analysis of material weaknesses. Academic work cited in the same verified data also reports that more than 500 companies, or over 3% of U.S. public companies, disclosed that prior financial statements shouldn't be relied on because of material error. Those figures concern public companies, not every small business, but the lesson travels well: controls are an error-prevention system, not corporate wallpaper.
The fifth moment is exit preparation. Buyers ask whether revenue is real, margins are repeatable, liabilities are complete, and the owner is still the only person who knows where everything lives. A bookkeeper can maintain the records. A CPA can help prepare quality-of-earnings materials, support financial statement assurance, and expose weaknesses before the buyer's team finds them.
| Scenario | Non-CPA Outcome | CPA Outcome | Typical Cost Gap |
|---|---|---|---|
| Multi-state or international activity | Transactions recorded, tax exposure potentially missed | Nexus, apportionment, and filing position analyzed | Varies by exposure and scope |
| Investor due diligence | Internal statements questioned or rebuilt under deadline | Reporting package prepared for outside scrutiny | Varies by deal requirements |
| IRS notice or audit | Founder handles technical correspondence or scrambles for help | CPA represents the taxpayer where authorized | Varies by matter complexity |
| Weak internal controls | Errors, fraud opportunities, and commingled funds persist | Controls are designed, documented, and tested | Varies by control environment |
| Exit preparation | Buyer discovers gaps late in the process | Financials and earnings support are prepared earlier | Varies by transaction scope |
Here's the uncomfortable truth: nobody can promise a precise break-even without seeing the business. But the pattern is reliable. If the non-CPA path creates rework, delay, exposure, or a failed financing process, the “savings” were just a deferred invoice with worse timing.
Titles create fog. Responsibilities clear it.
A bookkeeper owns recurring transaction work. An enrolled agent can prepare returns and has broad IRS representation rights, but an enrolled agent isn't the same credential as a CPA and doesn't provide the same audit and assurance function. A CPA handles the licensed work that connects taxes, financial statements, controls, and strategic decisions.
| Capability | CPA | Enrolled Agent | Non-CPA Bookkeeper |
|---|---|---|---|
| Tax preparation | Can prepare returns and advise on tax planning | Can prepare returns and advise on tax matters | May prepare returns if properly authorized, but scope and expertise vary |
| Corporate tax signing authority | Can sign returns within professional scope | Can sign returns within professional scope | Depends on credentials and authorization |
| IRS representation | Unlimited practice rights before the IRS | Unlimited practice rights before the IRS | Generally limited or unavailable |
| Audited financial statements | Can perform and sign audits under applicable standards | Not a substitute for CPA audit authority | Produces internal records, not audited opinions |
| Reviewed financial statements | Can perform reviews under recognized standards | Not a substitute for CPA review authority | Produces internal reports without assurance |
| Entity and exit advisory | Can advise on tax, structure, controls, and transaction readiness | Strong tax focus, but not CPA audit authority | Usually supports records and reporting execution |
| Software stack responsibility | Sets accounting policies and reporting requirements | May advise on tax-related data needs | Runs day-to-day workflows and reconciliations |
| Typical cost band | Premium, engagement-based pricing | Premium tax-focused pricing | Lower recurring bookkeeping pricing |
| Legal floor on sign-off | Licensed CPA standards and state rules apply | Enrolled agent rules apply | No CPA sign-off authority |
A bookkeeper at $40 per hour reconciling QuickBooks isn't interchangeable with a CPA signing a return or representing you before an auditor. That isn't an insult to bookkeepers. It's a job description.
Use the CPA versus bookkeeper comparison when you're defining responsibilities, then put those responsibilities in writing. The CPA should own tax planning, entity decisions, assurance work, controls, and high-stakes advisory. The bookkeeper should own transaction accuracy, reconciliations, accounts payable, accounts receivable, and the monthly close.
An enrolled agent fits when the main need is tax preparation or IRS representation without audit-level financial statement work. A non-CPA bookkeeper fits when the business needs clean, current records. The mistake is asking one role to impersonate another because the invoice looks smaller.
Founders usually hire a CPA too late, then describe the cleanup as “a little accounting project.” It isn't. It's archaeology with a deadline.
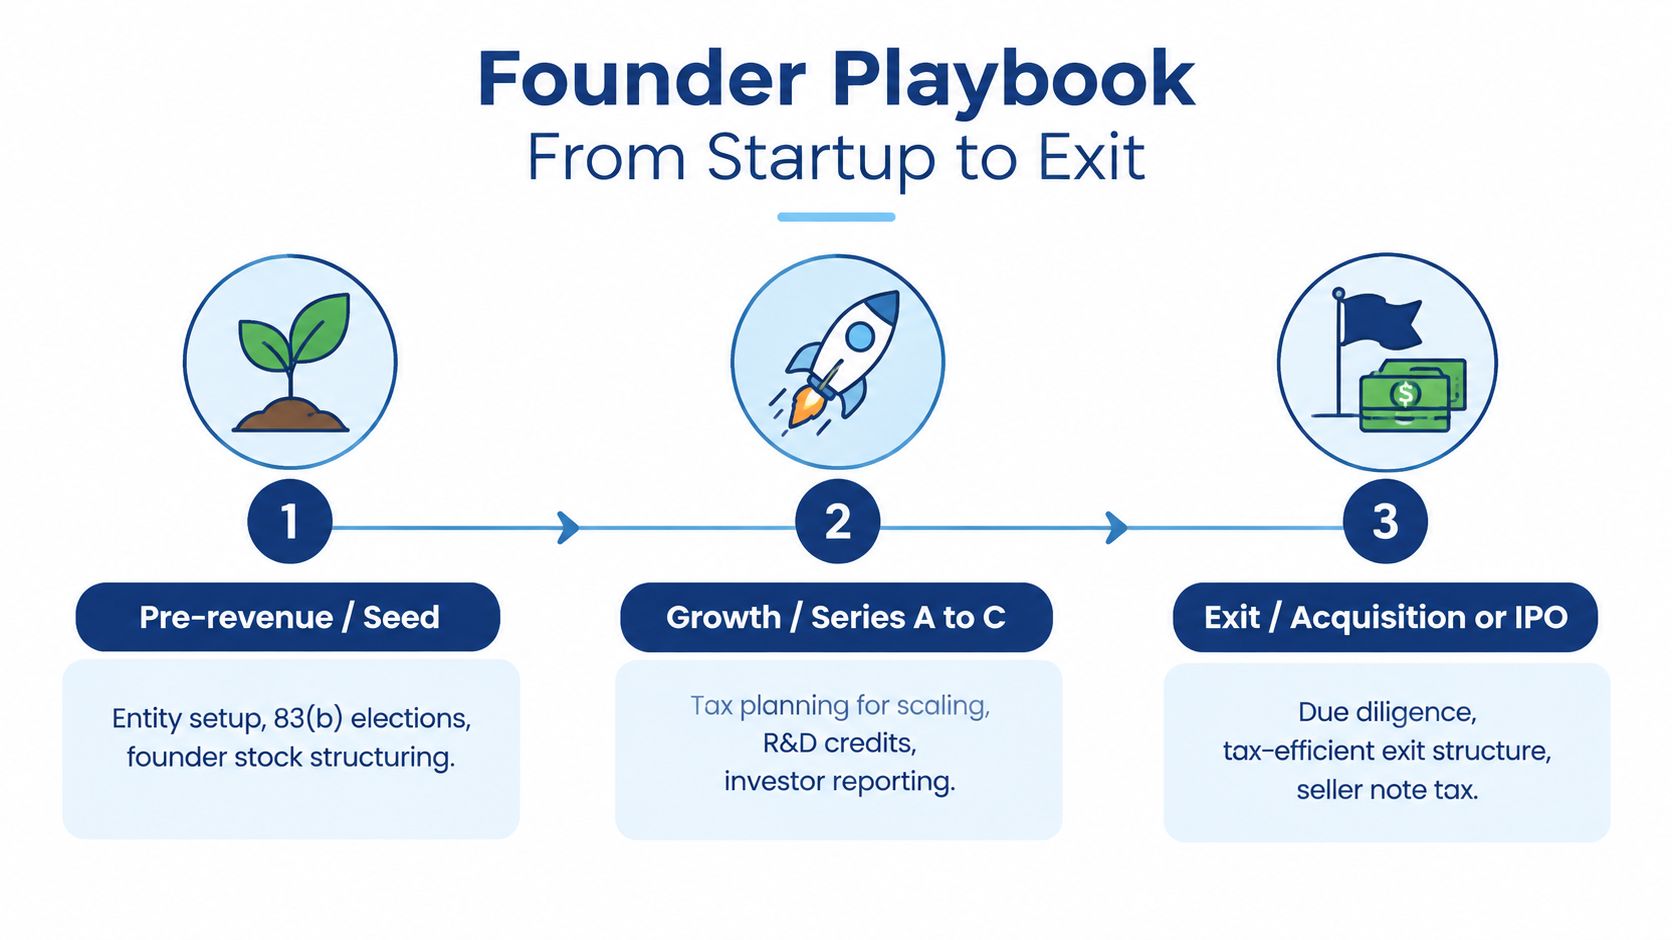
At the beginning, the CPA earns the check through decisions that become difficult to reverse. Entity setup, founder stock, vesting, 83(b) elections, research and development credit positioning, and the first cap-table review all deserve deliberate treatment.
The failure mode here is simple. A founder misses an election deadline, structures equity casually, or chooses an entity without considering the tax consequences. The company may still grow, but the cleanup lands when cash is scarce and everyone is busy pretending the cap table is “basically fine.”
A step-by-step startup guide for 2026 can help founders organize the broader launch checklist. It can't replace a CPA's judgment on the tax and accounting consequences of the specific structure.
Growth creates a different mess. The company needs books that can survive investor diligence, consistent revenue recognition, clear sales-tax processes, useful management reporting, and support for a debt round or outside financing.
Revenue somewhere between $1 million and $5 million is often where founders feel the strain described here, though the trigger is complexity, not a magic revenue number. The company has more contracts, more employees, more jurisdictions, and more people making financial decisions. A CPA should build the close process, document accounting policies, review tax exposure, and make sure the reports answer questions before lenders ask them.
Without that layer, the books may look tidy while the economics remain unreliable. That's how a company discovers during diligence that reported revenue needs reinterpretation, customer balances don't reconcile cleanly, or sales-tax exposure was never mapped.
At exit, the CPA becomes part accountant, part translator, part defensive midfielder. The work includes quality-of-earnings preparation, transaction-tax planning, sale-structure analysis, and support when the buyer's CPA starts hunting for weaknesses.
A buyer doesn't pay for optimism. The buyer pays for earnings they can understand and risks they can price. Financial cleanliness, recurring revenue, and owner dependence influence how an accounting practice is valued in 2026, with smaller owner-operated practices often trading around 0.7x to 1.4x annual revenue and larger firms commonly priced at 4x to 7x EBITDA, according to ExitLab's accounting valuation analysis. Those figures describe accounting firms, not every company, but they illustrate the broader point: clean, transferable operations support value, while owner dependence and messy records weaken it.
A CPA shouldn't just help you report the business. They should help make the business understandable without you standing beside it with a flashlight.
The right time to involve the CPA depends on the stage. Early founders need structural judgment. Growing companies need repeatable controls and defensible reporting. Exit-ready companies need a finance function that can withstand an unfriendly buyer's questions without collapsing into interpretive dance.
Start with the sales conversation. Don't ask only, “What do you charge?” Ask, “Tell me about the last difficult tax or reporting problem you solved, what made it difficult, what alternatives you considered, and what changed after the decision.”
A competent CPA should explain judgment in plain English. If the answer is a fog bank of acronyms, move along. You're hiring a professional to reduce confusion, not install more of it.
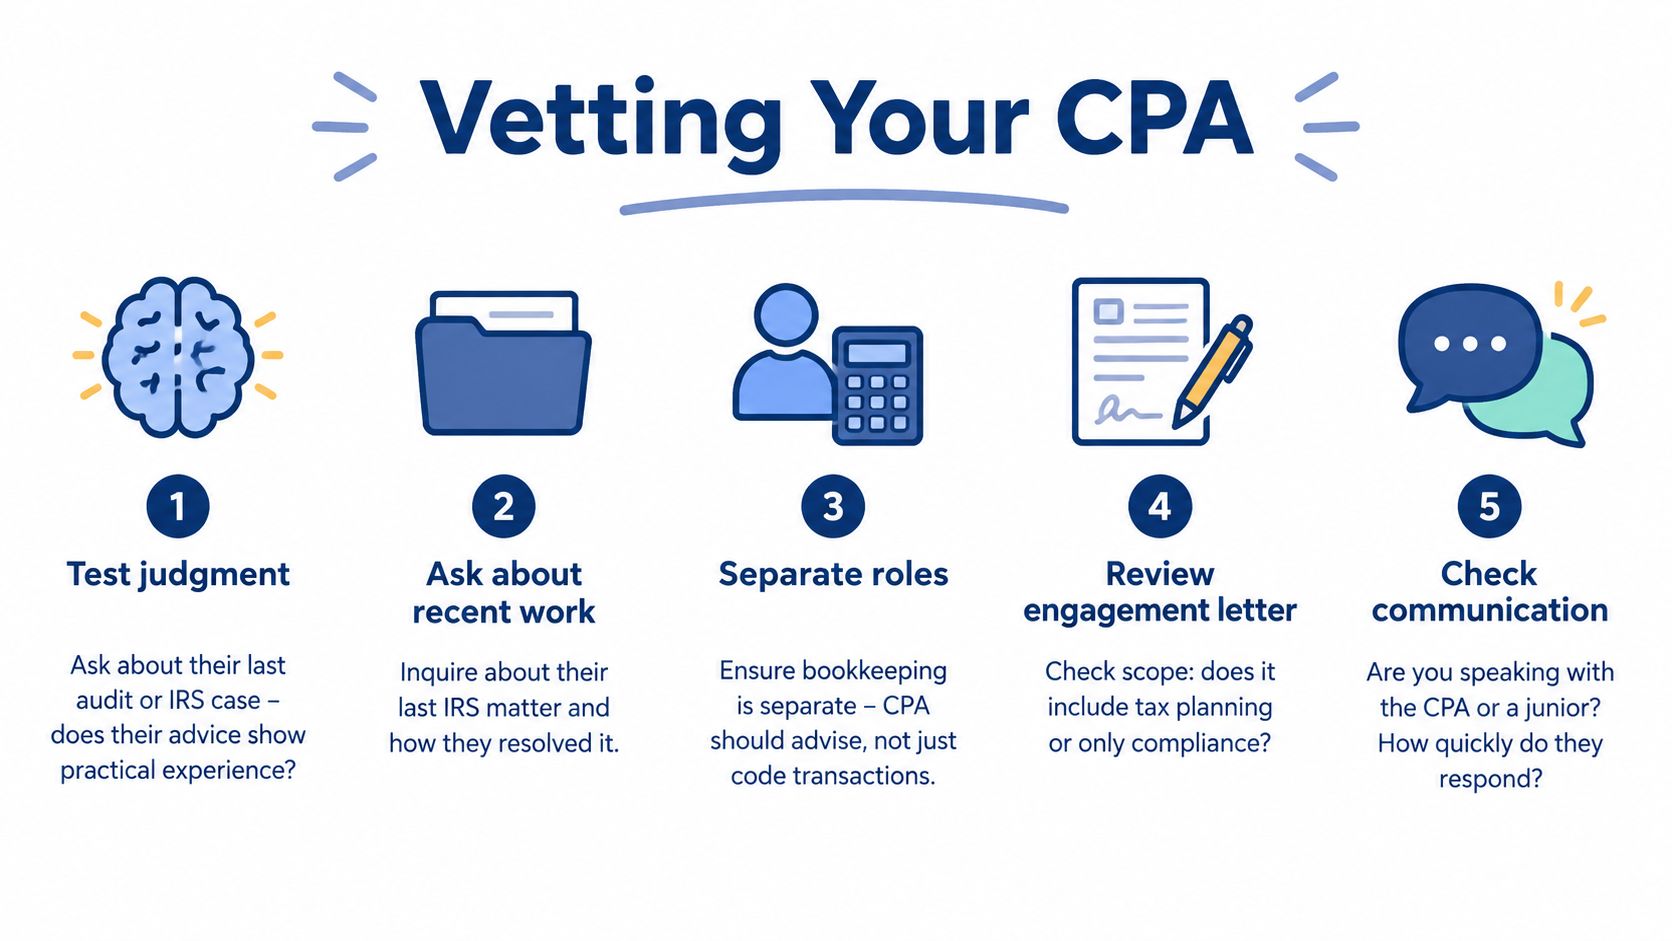
Use questions that force specifics:
The guide to hiring a CPA is useful for building an interview checklist, but your engagement letter matters more than any checklist.
Scope the work around outcomes. “Tax planning meeting, entity review, quarterly control review, return preparation, IRS representation if needed” tells you more than “accounting support.”
Keep bookkeeping separate whenever possible. A bookkeeper should own daily transaction work. The CPA should review the output, set policy, handle complex tax decisions, lead assurance work, and advise on the business. If a CPA refuses to delegate basic coding, bundles routine bookkeeping into an advisory retainer, or can't explain what they did on your return, you're looking at an expensive habit, not a finance strategy.
Put these terms in writing before signing:
The right CPA doesn't hoard every task. They build a team where each person does the work their skill level justifies.
Use one decision rule: when the cost of being wrong exceeds the cost of the CPA, hire the CPA.
Calculate the downside broadly. Include tax penalties, audit rework, missed credits, delayed financing, founder time, control failures, and post-close indemnity exposure. A mistake doesn't need to produce a dramatic tax bill to hurt. It can slow an investment, damage lender confidence, force a rushed transaction, or keep the founder trapped as the only person who understands the books.
The credential matters most when one of the three CPA-only jobs is approaching:
The visual below uses an illustrative comparison, not a universal price list. Its point is the math, not the specific quote.
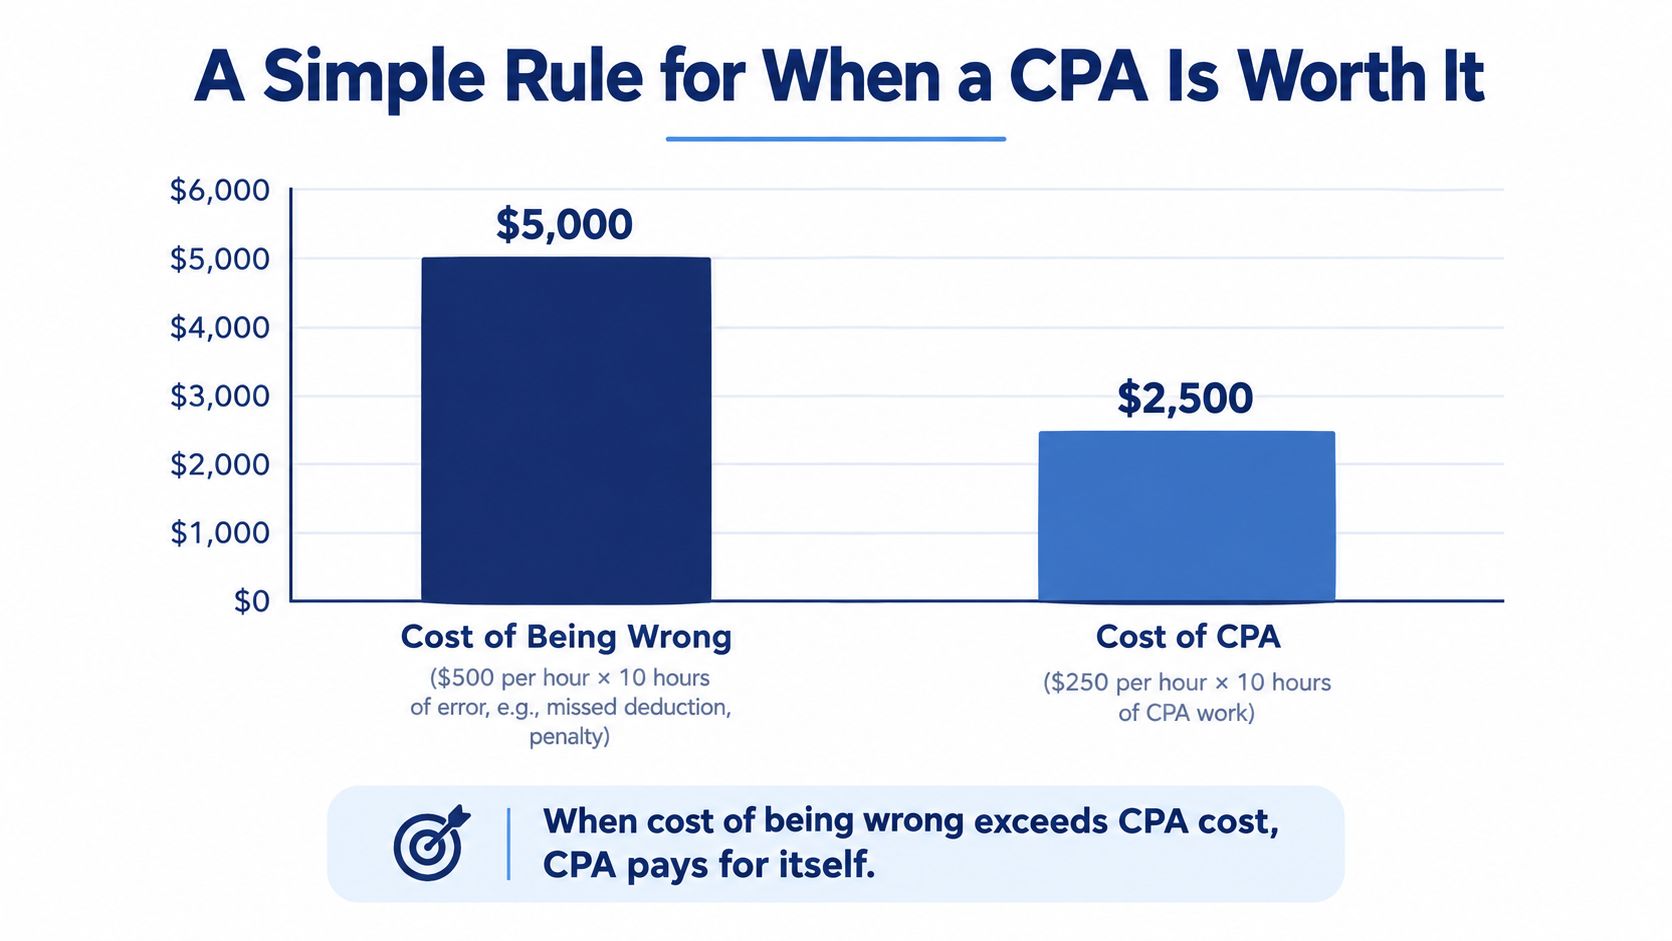
The trigger points are familiar: your first outside investor, your first full-time employee, your first six-figure tax position, your first audit notice, and your first acquisition conversation. Don't wait for all five. One can be enough.
A pre-revenue founder may need a single structure and tax-planning engagement. A scaling company may need quarterly CPA reviews alongside a bookkeeper. An exit-ready company needs a coordinated reporting, controls, and diligence plan.
Pick the next decision in front of you and hire for that deliverable. Don't buy a vague bucket of accounting hours and hope wisdom leaks out.
If you need clean transaction support or a CPA-led finance function, HireAccountants connects US companies with pre-vetted accounting and finance professionals, including CPA candidates for defined engagements. Visit the platform, separate bookkeeping execution from CPA-level judgment, and ask for a scope that matches the risk you're carrying.
Let's simplify your finances today!